저자: BillGross · 외국인
요약 보기
결론: 빌 그로스는 경기침체를 크게 우려하지 않으며 시장 하락은 예상된 조정이라고 보고, 보수적 운용과 할인 자산 매수를 권한다. 시장 상황: 최근 몇 달간 시장이 하락한 것은 예상했던 결과이며, 레버리지가 높은 글로벌 경제에서 연준의 금리 인상 이후 가격 하락 압력이 나타나고 있다고 진단했다. 펀드 운용 방식: 해당 펀드는 5~10% 수익을 노리는 것이 아니라 자산을 지키면서 완만한 수익을 얻는 것을 목표로 하는 보수적 펀드라고 설명했다. 저금리 정책 부작용: 장기간의 저금리는 주택 구매에는 유리하지만, 예금자와 보험사·연기금 등 고금리가 필요한 기관에는 손해를 준다고 지적했다. 통화정책 한계: 중앙은행은 0% 금리와 양적완화가 성장을 거의 만들지 못한다는 개념적 모델이 없으며, 정책이 막다른 길에 이르렀다고 평가했다. 글로벌 공급 과잉(원자재 포함)도 이러한 정책이 키운 문제라고 봤다. 신용 위험: 미국 가계부채는 줄었고 저금리로 소비자 상황이 양호해 미국 내 디레버리징 위기는 걱정하지 않는다. 다만 달러 표시 부채가 많은 브라질 등 일부 국가는 달러 강세 시 부채 부담이 커져 위험하다고 봤다. 전이 리스크: 시장이 상호 연결되고 헤지펀드 등 레버리지 투자자가 많아, 가격 하락 시 마진콜로 인한 투매가 우량 자산까지 밀어낼 수 있다고 경고했다. 투자 조언: 안전하게 가려면 할인된 자산을 매수해야 하며, 액면가 85~90% 수준에 거래되는 폐쇄형 펀드를 선호한다. 예시로 BlackRock Build America(BBN, 미국 정부 준보증, 수익률 약 7~8%)를 추천했지만 가격 하락 가능성은 여전하다고 덧붙였다.
다듬은 글
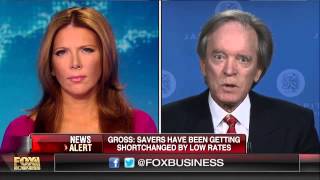
With many bigname stocks plunging into bare territory and fears of a systemic debt crisis all of 2008 driven by investors once insatiable appetite for yield. We want to know is this recent market selloff just a selloff or is there something bigger and more problematic going on? Well, the guy who knows more than anyone about debt markets is legendary bond investor Bill Gross portfolio manager for the Janice Global Bond Fund.
and he is here right now with a look at how you can best position yourself. Bill, welcome. Hey, Trish. Uh, good to be here. You know, I got to say it's a really tough market right now, but I know your fund has beaten about 80% of your competitors since you started. So, first of all, a big congratulations to you on that.
Hey, thank you. And second of all, we want to know how you've done it. Well, uh we've done it by lots of research, lots of hard work, and uh being conservative. You know, obviously in the past several weeks, in the past several months, markets are moving down as opposed to up. And it's just what uh we expected.
We basically were looking um at a highly levered global economy that was subject to, you know, pockets of downdrafting in in terms of prices once uh the Federal Reserve started to raise interest rates. And we're seeing just that. And so it's a it's a conservative fund. It isn't intended to yield five or 10%.
It's intended to basically save your money and to earn a modest return. And that's what it's doing. You know, Bill, over the last couple of years, you have repeatedly told me that you were worried about the dangers of central bank planning, that you just couldn't sort of leave the spigot on forever, and there are a lot of uh perhaps unintended consequences of leaving interest rates too low for too long.
Do you think the chickens are coming home to roost right now? Well, I think they are. Uh, and there are negative aspects to low interest rates as opposed to positives. You know, the positives would be your mortgage is cheaper at a lower interest rate and you can buy a bigger house. Uh the negatives basically are that that savers you know your viewers who have invested uh their deposits in banks for the last six or seven years at basically 0%.
You know basically are getting short changed and and that uh extends not only to individual savers but to insurance companies, pension funds and other institutions that uh need higher interest rates. And so, yes, the chickens are coming home to roost, so to speak. How how big a deal could this be? I mean, we we've had some people on the show, and I want to get your perspective on this that are that are quite concerned because the feeling is the Fed is out of ammunition right now.
Our economy is still in lousy shape and there's all this high yield junk out there that could potentially default. I mean, you think about MLPS and, you know, some of the the loans that maybe have been made to Chinese companies, some of the sovereign debt that exists out there. What's your view of the credit quality situation for some of these?
Sure. Those are excellent points and and and I would say from 30,000 ft that there's simply too much supply uh relative to demand in the global economy not just in oil but in most commodities and related investment in producing them. And you know that supply has been fostered as we mentioned by years of 0% interest rates in quantitative easing.
At the moment, you know, policy makers uh which include central bankers, you know, they have no conceptual model to explain why 0% interest rates produce relatively little if any growth and you know, they look to the job market and they fear inflation, you know, two or three years forward yet, uh financial markets expect much less than they do.
So, you know, I think part of the problem is monetary policy. It's reached sort of a dead end. I I think central bankers are following the wrong road map and are reluctant to call home for directions. Are you worried about a credit crisis, a debt crisis similar to what we saw different from but similar to 2008 at all?
Well, we see that in certain pockets around the globe and and you see a potential crisis when you have too much debt in the United States. you know debt has been reduced in terms of household debt. A lot of mortgage debt has come down. Some of it is uh as a result of defaulting but in any case the homeowner uh the US consumer is in a relatively good position with low interest rates and low debt.
So I don't worry about that. Uh there are some countries however that have taken on a lot of debt. You mentioned it a few minutes ago. you know, Brazil for example, uh, in dollar denominated terms and as the dollar appreciates and their currency goes down, that means their liabilities go higher and higher and higher.
And so, you know, there there are pockets around the world where there's a lot of debt and it's dollar denominated and we're seeing some of that in terms of the problem areas in markets. Does it matter to us though? I mean, you know, if if Brazil's struggling or or even China for that matter, how much should it matter to us investors?
Well, it should matter a lot because that the markets these days and these years, you know, not 20 years ago, but these days, the markets are basically interlin and interconnected. Um, and and and they're relatively highly levered, too. um meaning hedge funds, meaning um you know investors that have borrowed money in order to take uh higher yielding positions.
As as prices come down, uh this isn't hard to explain and it's relatively easy to understand. As prices come down, there are margin calls and levered investors basically have to sell things in order to meet margin. And sometimes they even sell highquality investments because those are the easiest things to sell.
And so, you know, high debt basically leads to a downdraft when uh interest rates start going up as Okay. So, if you're one of those worried investors right now that that is scared about this scenario you're playing on, I just have 30 seconds, but what would you tell them to do? Well, you got to be safe and and you've got to buy assets at a discount.
I like closed in funds where you can buy assets at 85 to 90 cents on the dollar. Best example, uh, BBN is the symbol, Black Rockck Build America, semi- guaranteed by the United States of America. It yields about 7 to 8%. You know, does that mean the price doesn't go down? No. Uh, but it's been relatively secure and safe, and I recommend that much. Good to have you here, sir, as always. Thank you.



Comments 0