저자: Farzad · 외국인
요약 보기
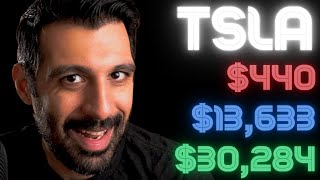
개인 투자자 Farzad가 2013년부터 유지해온 테슬라 밸류에이션 모델을 바탕으로 2035년까지 bear/base/bull 시나리오별 주가와 시가총액을 제시한다. 자동차(연 생산량·판가·순이익률), AI(FSD·로보택시·봇), 에너지 사업을 각각 가정해 합산한다. bear는 약 440달러(PE 15, 시총 1.65조 달러), base는 약 14,000달러(시총 41조 달러), bull은 약 30,284달러(시총 91조 달러) 수준을 제시하며, 자신은 투자 조언이 아니라 장기 성장 가능성을 가정해 보는 취미 모델이라고 강조한다. 현재 주가 대비 상승 여지를 말하지만 1~3개월 단기 방향 예측은 없다.
다듬은 글
i've been keeping a tesla stock valuation model since 2013 and i posted the first version on reddit to get feedback from the r investing subreddit community i was predicting roughly half a million cars sold by 2021 and a market cap of a little bit over 50 billion almost all the comments on that threat were telling me how wrong i was getting this story and that it was going to be impossible for tesla to reach those heights unfortunately for the both of us we were wrong tesla price went well beyond both our expectations however if you do want some entertainment i've left the link to that reddit thread in the comments this is something i've done purely for fun over the years some call this a hobby i call it a really nerdy thing i do because i'm probably not busy enough but these models have helped me think through the long-term potential of companies and tesla in particular have shown insane growth prospects in the last few years let me be very clear this is not financial advice some sort of stock price predictor or anything that resembles information that you should be basing your financial decisions on it's a tool that i've used to understand what the potential implications are from a market perspective and to see if thinking in a specific way about tesla's long-term growth makes reasonable sense however i must warn you when it comes to tesla the numbers tend to get large and sometimes completely ridiculous i've tried my absolute best to apply a logical approach to the best of my abilities but enough of that let's get into the meat of things i've broken the models into three cases bear bass and bull bear will be my worst case scenario at about 25 likelihood base is what i think is most likely at 50 likelihood and bull is my best case scenario at 25 likelihood each of the cases have four main pillars that drive the company's revenues and profitability transportation ai energy and outsource outsource won't come into play until the bold case scenario let's start with the bare case with the following assumptions starting with transportation tesla will be able to reach a production rate of 7.5 million cars per year by 2030 and 9.5 million by 2035.
this will be through their existing fleet and introduction of new models such as cheaper cars cyber truck semi etc even under my bear scenario i believe the market for evs is so large and so untapped that tesla will grow into it as long as they make cars there's currently 1.4 billion gas vehicles in the world and thus far about 20 million evs have been made in the world that means that there's still 1.38 billion evs to be made in the coming decades that's a lot of evs however as far as tesla goes i assume that their max capacity is roughly half of elon's stated goal of 20 million cars per year let's assume a little under 10 million cars i'm assuming an average selling price of roughly 42 thousand dollars for these vehicles this does not include fsd we will cover this later on and as far as profitability of this business i assume that it goes down over time from roughly 20 of revenues flowing to net income down to 15 percent if we extrapolate these numbers out this is what revenues and net income look like for this division in 2035.
403 billion dollars in revenue and 60 billion in net income now let's do ai for ai i assume that full self driving doesn't turn into the level 4 or 5 system that tesla has promised but instead into a highly usable level three system that roughly fifty percent of the customer base will purchase at twelve thousand dollars per vehicle at eighty percent margin to tesla i also assume that the robo taxi network never comes to fruition as well as the bot therefore zero dollars are contributed from these two for ai in 2035 revenues come in at 48 billion and net income of 39 billion due to the very high margin and lastly for energy elon has often talked about energy coming to parity with the auto business over time i assume that this never happens and instead reaches roughly 20 of the size of auto by revenue by 2035.
energy revenues in 2035 come in at 75 billion and 11 billion of net income under this scenario i also assume a 2 dilution in shares each year which lowers stock price relative to market cap if we combine all these variables together this is what car units revenues net income market cap and stock price look like through 2035.
i assume a compression and pe down to 15 as the company grows and reaches stabilized growth which forces the stock price to come down as time goes on relative to profits made by the company as well as the effects of dilution to shareholders by 2035 this exercise shows a post-split stock price of roughly 440 per share and a market cap of 1.65 trillion dollars at a p e of 15.
this target is roughly 47 higher than current levels as of this recording or a 3 compound annual growth rate which is 500 basis points lower than inflation not the best investment one could argue but now let's move on to the base case for transportation i'm assuming tesla reaches their goal of 20 million cars per year around 2032 which is two years after elon's slated goal like the bear case tesla will achieve this through introduction of new models and adoption of current ones but at a higher rate roughly double over the bear case and i assume an average selling price of 45 000 per vehicle slightly higher than the bear case like in the bear case this does not include revenues from full self driving we will cover this later on i assume they're able to reach 25 of transfer revenues flowing down as net income which is 500 basis points higher than today this is due to their increasing competence in manufacturing automation and other improvements through new gigafactories to sum it up i assume tesla reaches its goal of 20 million cars per year later than expected at an average selling price of 45 000 per car and 25 net income the transportation division in 2035 would bring in one trillion dollars in revenue and 250 billion dollars in net income after extrapolating these figures now for ai i assume full self driving fulfills its promise of level 4 autonomy and paves the way for level 5.
under this scenario i'm modeling full self driving being sold at 25 000 per vehicle with additional revenue generated per year per vehicle in the fleet with fsd i assume five percent of vehicles sold to consumers generate six thousand dollars to tesla by way of them keeping twenty percent of revenue generated by fleet operators i assume these operators would make roughly thirty thousand dollars a year before tesla takes a cut which mirrors how much the average uber driver makes per year in the united states however i think the cost per mile would be significantly cheaper it's just that the vehicle would effectively be working 24 7 so the total miles driven per year will be significantly higher i also assume another five percent of the fleet that's owned and operated fully by tesla and generates thirty thousand dollars per year per vehicle this is basically like the fleet model but without the fleet runner here tesla would keep a hundred percent of the profits i'm also assuming tesla will generate an additional five thousand dollars of revenue per year per car from eleven percent of the fleet this can be folks leasing fsd future in-car entertainment apps etc and lastly for the bot i assume zero dollars contributed by the bot in my base case the bot still does not exist all the ai line items i've listed so far will be sold at 80 margin just like the bear case putting all this together the ai division in 2035 would bring in 1.3 trillion dollars in revenue and 1.1 billion dollars in net income it becomes quite clear in the base case how ai can be incredibly impactful 80 margins for software becomes a giant profit generator for tesla and lastly for energy i assume tesla reaches close to 50 percent of the car business size still not quite at parity with the car business but getting closer this division in 2035 would generate 476 billion dollars in revenue and 119 billion dollars in net income now to put it all together i assume that dilution stops around the year 2024 due to the insane amount of cash tesla will be generating after this point given elon's recent comments around the buyback program i think this trend repeats itself more than a few times this decade which will help keep shares outstanding relatively stable here's a full breakdown of the same variables we showed for the bear case but with base case assumptions by 2035 this exercise shows a post split stock price of roughly 14 000 or a market cap of 41 trillion at a pe of 27.6 which is roughly 4 400 percent higher than a current price levels or a 34 annual compounded growth rate that's a pretty damn good return of investment if you ask me and lastly let's review the bulk case and see where things can get real crazy if you haven't already felt that they were crazy enough for transportation nothing changes from the base case i see the market behaving exactly the same way from number of units sold and average selling prices so 22 million cars sold per year at 45 000 average selling price at 25 net income this division would bring in the same level of profitability as in the base case one trillion dollars in revenue and 251 billion dollars in net income now where things start to change is in the ai side of the business i assume tesla earns about the same from each car sold from fsd twenty five thousand dollars to purchase the software six thousand dollars from fleet operators per car per year and thirty thousand dollars from vehicles operated by tesla as well as five thousand dollars per year from the fleet from entertainment fsd leasing etc where things change is what percentage of the fleet adopts each one of these variables i assume tesla remains at the same five percent of the fleet being owned and operated by tesla but i assume 20 percent of the fleet is owned and operated by fleet runners and 20 of the fleet is opting into entertainment options fsd leasing etc these again would run at the same prices as the base case but now we finally got the bot making an appearance given elon's recent comments where a bot would cost less than a car and folks would be able to gift it to their parents i assume a price of around 25 000 for the bot by 2035.
by then i'm assuming tesla is selling about 25 million of these units per year with each bot averaging around 30 000 of revenue to tesla per year as they are hired for different tasks think of this part of the bot as buying apps to complete jobs want to fold clothes buy the clothe-folding app for a hundred dollars or pay five dollars per job want to build a house pay a thousand dollars per bot per job so on and so forth i land at 30 000 per year by mirroring the average wage per year for laborers in the us and assume that the bot can do six times the effective work of a typical human in these scenarios i assume the bob will be twice as fast and can work almost 24 hours a day which is three times longer than the average human so the cost per job would be roughly six times less but it can do six times more in any 24 hour period and again that would be roughly 25 million bots running around with these capabilities so after putting all these ai variables together in 2035 this division would bring in 2.1 trillion dollars in revenues and 2.2 trillion dollars in net income but wait you may ask how the hell is tesla making over a hundred percent on net income that's the magic of recurring revenue at scale by this point if our assumptions are correct tesla would have roughly 120 million teslas driving around and 50 million bots running around each of these generating income for the company and the crazy thing is these numbers get bigger the further we go into the future as tesla's scale stabilizes to maximum yearly capacity this is why master plan part 3 is so exciting we'll finally get some insight into what elon and tesla are planning from a scale perspective now for energy i'm assuming tesla and elon are able to reach their goal of coming to parity with the transportation side of the business for revenues i'm assuming 968 billion dollars and 242 billion dollars in net income by 2035.
essentially think of energy as a twin brother of transport without the fancy ai revenue however what's scary about that statement is that tesla has talked about energy arbitrage as a key factor for their energy plans and this could be yet another revenue generator for tesla that is not included in this model and lastly for outsource i'm assuming tesla will sell batteries and drive trains to other manufacturers by this point given their dominance from a technology and cost perspective this will be quite small relative to the rest of the business at 98 billion dollars in revenue and 24 billion dollars in net income quick note i'm not including anything related to revenues from insurance or anything else elon and tesla might get into if any of these do appear in the future it's gravy to this valuation and so here is the full summary of the bookcase for tesla by 2035.
like the base case i assume tesla initiates a buyback plan starting in 2024 and keeps outstanding shares relatively stable into the future by 2035 this exercise has the bulk case post split stock price at 30 284 or a 91 trillion dollar market cap at a p e of 33.6 which is almost 10 000 higher from current prices or an average yearly return of 42.6 from 2022 until 2035.
now you're probably asking yourself how in the hell are prices like these possible and how can a market cap reach such absurd heights the main criticism i get when i throw out price targets like these is that current global gdp is roughly 86 trillion how could a company be valued the same as a yearly global gross domestic production here's my pushback market caps are a reflection of future total profits generated by a company so an effective market cap of 91 trillion dollars doesn't mean that tesla is larger than the size of the economy of planet earth it means that the market is expecting tesla to generate 91 trillion dollars of profits for the rest of its existence in this case since we use the pe of 33.6 this means that the market is expecting tesla to generate the profits they are generating in 2035 for 33.6 years this is an incredibly important distinction if the company has excellent execution moats in multiple industries and is at the cutting edge and forefront of automation ai and robotics why wouldn't it deserve this sort of valuation in addition in an age where automation robotics and ai are constantly improving and doing so quickly it stands to reason the value generated each year will be much larger than years previous this means that the future is constantly getting better and more valuable faster when we add the acceleration of ai robotics and automation what does the future look like i'm of the opinion that folks unwilling to recognize bull case scenarios like these are discounting the revolutions that are happening in the field of technology and discounting tesla's previous executional excellence and incredibly talented workforce but who am i to say i'm just a random dude on the internet i hope you found this video helpful if you did i would love it if you throw me a like so the youtube algorithm can show this to more people if you'd like to join our growing community over on discord consider becoming a patreon or joining through youtube your support is never required but always appreciated and lastly i've posted a link to the full model in the description for you to view i'd love to hear your feedback in the comment section what are your thoughts what am i missing what am i getting wrong do you agree with the approach let me know thanks again once again and we'll see you in the next one take it easy bye sheesh


Comments 0