원문 보기
Well, hello again. Welcome back to the playbook. Last week, we talked about why people invest. We talked about freedom, about choice, about buying your time back. Today, we're going to talk about the mechanism that makes all of that possible. It's called compound interest. Section two, the power of time.
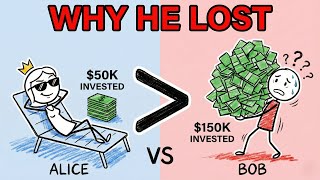
Imagine three people, same age, same income, different decisions. Let's call them Alice, Bob, and Brian. All three earn $50,000 per year. All three decide to invest $5,000 per year. That's 10% of their income, a reasonable amount, not extreme. Now, here's where they differ. Alice starts investing at age 25.
She does this consistently for 10 years. Then she stops. She gets tired. She needs the money. Life happens. So, she invests $5,000 per year from age 25 to 35. That's 10 years. Total invested, $50,000. Then she stops. She puts the money in a safe place and leaves it alone. Bob starts later. He doesn't start until age 35.
But once he starts, he's more disciplined. He invests $5,000 per year from age 35 until age 65. That's 30 years total invested. $150,000. He invests three times as much as Alice. Brian. Brian is somewhere in the middle. He starts at age 30 and invests $5,000 per year until age 60. That's 30 years. Total invested $150,000.
Same as Bob. Now, let's say all three investments grow at 10% per year. This is the historical average of the stock market. This is reasonable. This is not optimistic. By age 65, how much do they have? Alice invested $50,000, but her money grew for 30 years after she stopped investing. Her $50,000 became approximately $1.53 million.
Bob invested $150,000. He invested three times as much as Alice, and he was consistent for 30 years. His $150,000 became approximately $900,000. Brian invested $150,000, the same as Bob, but he started five years later and stopped five years earlier. His money became approximately $1.47 million. Think about what just happened.
Alice invested the least, only $50,000. Yet by age 65, she has over $1.53 million. That's a 30 times return on her money. Brian invested three times as much and he became a millionaire. That's the power of consistent investing. But here's the part that should grab you. Bob invested the same as Brian, $150,000.
But because he started 5 years later, he ended up with $900,000, $570,000 less than someone who invested the exact same amount he did. This is not because Brian was smarter. This is not because he was luckier. This is because his money had five more years to compound. Five years. That's all the difference.
And if Alice had kept investing, if she hadn't stopped at 35, but continued until 65, she would have had nearly $2.5 million by 65. $2.5 million from investing $5,000 per year for 40 years. Section three, the mechanics. Now, let me explain why this happens. Because the mathematics are almost magical.
When you invest money, it doesn't just sit there. It grows. Let's say it grows at 10% per year. That's the historical average. Year one, you invest $5,000. It earns 10%. That's $500 in earnings. Your total $5,500. Year two, you invest another $5,000. But now your first $5,500 earns 10%. That's $550 plus your new $5,000.
Your total $11,50. But here's the key part. Your earnings are earning earnings. Year three, your $11,50 earns 10%. That's $1,15 in earnings plus your new $5,000. Your total $17,155. Do you see what's happening? The earnings are compounding. They're growing on themselves. In year one, you earned $500.
In year three, you earned $1,15. You didn't put in more money, but you earned more than twice as much because your previous earnings are now working for you. This is compound interest. This is the eighth wonder. It's not linear. It's exponential. In the early years, it looks slow, boring, even. Your money is creeping up.
year one, year two, year three, you're thinking, is this worth it? Is this actually doing anything? But then something happens around year 15 or 20. The money starts accelerating. The growth speeds up. The earnings start compounding faster and faster. By year 30, your money isn't just growing. It's growing rapidly, explosively almost.
And the later years become worth more than all the earlier years combined. Let me show you with actual numbers. If you invest $5,000 per year for 40 years at 10% annual growth, years 1 to 10, you'll have about $69,000. Years 1 to 20, you'll have about $316,000. Years 1 to 30, you'll have about $1.06 million.
Years 1 to 40, you'll have about $2.84 million. Look at those numbers. In the first 10 years, you get $69,000. In the next 10 years, years 11 to 20, you go from $69,000 to $316,000. That's a $247,000 gain in a single decade. In years 21 to 30, you go from $316,000 to $1.06 million. That's a $744,000 gain.
In years 31 to 40, you go from $1.06 million to $2.84 million. That's a $1.78 million gain. The last 10 years produced more wealth than the previous 30 years combined. This is compound interest. This is why time is more powerful than income. Section four, time versus effort. Now, here's something that most financial advice gets wrong.
They tell you, "Invest more, save more, cut your expenses." These things are helpful, but they're not the secret. The secret is time. Time beats effort every time. Now, you cannot control how hard you work. You can work hard, but you might not earn much. You might be a teacher or a nurse or a farmer.
You work extremely hard, but don't earn a huge income. The good news, you don't need a huge income to become wealthy. You need time and consistency. And here's the problem. Most people feel like they don't have time. They're young. They have their whole lives ahead of them. So, they think, "I'll start investing next year or the year after when I'm more stable, when I earn more." And then they're 35 and they think, "I'll start when I pay off my house or my car or my student loans." And then they're 45 and suddenly they realize they've wasted 20 years.
and compound interest. This most powerful force in building wealth has been compounding against them. Not for them. Section five, the interruption. Now, there's one more thing you need to understand about compound interest. It's fragile. Despite being the most powerful force in investing, it's incredibly fragile.
It can be interrupted. You don't have to stop investing entirely. You just have to interrupt it. You invest for 10 years. You're on track. Then the stock market crashes. You panic. You sell everything. You wait for it to stabilize. Now you've interrupted the compounding. Your money is in cash, earning nothing while it waits.
The market recovers, but you've missed the recovery. By the time you feel safe enough to get back in, months have passed, a year, sometimes years. You just lost decades of compounding from that single decision. Or you invest for years and then you need the money. A medical emergency, a job loss, an opportunity you don't want to miss.
You withdraw from your investments early, pay taxes on the gains, and pay penalties. The compounding is interrupted. Or you invest consistently, but then you think you're smarter than the market. You try to time it. You sell when the market is high. You wait to buy back in when it's low, but you miss the timing.
You buy high and sell low, which is the opposite of what you're supposed to do. The compounding is interrupted. The first rule of compounding is never interrupted. Think about that. The first rule, not the second rule, not a suggestion. The first rule, never interrupt the compounding. Don't panic sell.
Don't try to time the market. Don't withdraw early for emergencies unless they're genuine life ordeath situations. Just let it compound. Let time do its work. So, here's what I want you to understand about compound interest. It's not complicated. It's not mystical. It's simple mathematics. Money grows.
The growth earns more growth. The more growth earns even more growth. This continues for years and decades. In the early years, it feels slow. You wonder if it's worth it. In the later years, it becomes extraordinary. It becomes the difference between desperation and freedom. And the sooner you start, the less you have to contribute.
A person who starts at 25 and invests $5,000 per year for 40 years can end up wealthier than a person who starts at 35 and invests $20,000 per year for 30 years. Same starting salary, different time horizons, dramatically different outcomes. This is why I told you in the last video, the most important decision you make is not what to invest in, it's when to start.
Starting early is everything. It doesn't matter if you start with $100 or $500 or $5,000 per year. It matters that you start. And it matters that you never interrupt the compounding. The eighth wonder is waiting for you. Time is your ally. Money working for you. Earning earnings that earn more earnings.
This is how ordinary people become wealthy. But only if they start and only if they never interrupt it. The question is not whether compound interest works. It does. The question is whether you'll let it work for you. Next week, we're going to talk about what you're actually buying when you invest because it's not what most people think.
Until then, think about compound interest. Think about starting. Think about never interrupting it. That's where the real wealth comes from.


Comments 0