원문 보기
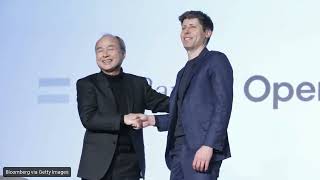
In late 2022, billionaire tech investor Masayoshi Son completely retreated from the public eye. His vision fund was reeling from failed bets on startups like Weiwork, and he admitted to his investors that the scale of the losses brought him to tears. By June 2026, that era of retreat ended. Son was stepping out of a black Mercedes at the Elise Palace to be hosted by French President Emanuel Mcronone, the fourth world leader to publicly welcome him in just 2 years.
SoftBank had just officially ended Toyota's 23-year reign to become Japan's most valuable company. Son's personal net worth has reached roughly 100 billion. He has committed over $60 billion to OpenAI and is currently directing another $52 billion into data centers across France. This turnaround relies on a highly leveraged highwire act.
Rather than simply picking winning tech stocks, Son engineered a complex loop of circular transactions to move capital between his own companies and generate massive spending power. Soft Bank's shift toward AI is powered by aggressive debt. To fund these multi-billion dollar commitments, San treats debt as his primary fuel source.
Rather than relying on liquid cash reserves to get that money, Soft Bank relies on its existing assets. They hold a massive stake in the chip designer ARM Holdings and they borrow billions of dollars against the rising value of those shares to secure fresh cash. Soft Bank then takes that borrowed capital and plows it directly into OpenAI.
This includes a $32 billion investment in 2025, followed by an additional $30 billion this year. By borrowing against the value of one tech asset to fund another, SoftBank generates enormous liquidity. However, this strategy builds a sprawling AI empire on a foundation of debt. To keep this system running, SoftBank relies on circular transactions.
Instead of spending that borrowed money solely on outside vendors, they circulate it between their own portfolio companies. For instance, Soft Bank pays its own subsidiary, ARM, $74 million for a chip development project. That single internal payout accounted for 60% of ARMs revenue growth over a 12-month period.
Then SoftBank agrees to pay OpenAI $3 billion every year for a yetto-bereleased product called Crystal Intelligence. With that fresh capital in hand, OpenAI signs a lease to rent a massive 1.2 gawatt data center from SoftBank at a cost of roughly $2 billion a year. By routing its own borrowed cash through its own subsidiaries, SoftBank acts as both the primary funder and the biggest customer within its ecosystem.
This effectively increases the reported revenues and valuations of its portfolio using its own leverage. The physical infrastructure required for this loop, massive data centers, carries a multibillion price tag. Soft Bank covers 80 to 90% of these costs through project finance, securing outside loans once tech companies sign long-term leases.
To extract even more outside cash, Sun is preparing to spin off internal divisions like the robotics unit Rose AI and the energy company SB Energy into public stock offerings. Meanwhile, SoftBank's board approved a $3.1 billion loan directly to Masayoshi Sun. This personal loan gives him a 17.25 25% cut of the profits from the specific fund investing in OpenAI.
This legal maneuver isolates Sun from the downside. The public shareholders bear the risk of the fund's massive 139 billion exposure. While Sun is positioned for a personal payday if the gamble succeeds because this entire ecosystem is tied together by shared momentum, it is acutely vulnerable to a slowdown.
If the broader AI market cools, the stock price of ARM holdings would likely fall, shrinking the collateral Soft Bank uses to secure its debt. This could trigger a cascading effect. With less collateral, SoftBank loses its ability to funnel billions into OpenAI. Without those regular injections of SoftBank cash, OpenAI would struggle to pay the $2 billion in rent for SoftBank's data centers.
Sun is open about this fragility. He admits that a market downturn on the scale of the dotcom bust could happen at any time. He has experienced this before. Over 20 years ago, the original dot bubble burst and wiped out 99% of SoftBank's total value. Sun describes these market crashes as moments of evolution.
In his view, the strongest survivors emerged 10 or 100 times more powerful, and he is positioning SoftBank to be the primary architect of that future.


Comments 0