저자: 에릭/레이달리오견해인용 · 한국인
요약 보기
레이 달리오의 칼럼·인터뷰를 인용해 트럼프 2기에 세계가 1930년대와 유사한 민족주의·보호무역·국가통제 국면으로 간다고 설명. 미국 경제는 AI 군비경쟁과 고성장·고물가 속에서 당분간 견조하며 S&P500은 추가 상승 여지가 있으나 밸류에이션 부담으로 비중 확대보다 분산 권고. 미국 주식 기대치가 높아 신흥국(글로벌 사우스, 인도 등)이 상대 유망. 채권의 분산 효과 약화로 금이 대안, 달러 안전자산 지위 훼손 시 금 상승 전망, 원유는 박스권이나 이란 제재 시 상방 위험, 비트코인 성장 국면 언급.
다듬은 글
Hello, this is Eric. Today, I’ve brought a story about Ray Dalio, someone making an appearance after a long time. To briefly introduce Ray Dalio first, he was the founder and chairman of Richwater Sierra, the world’s largest hedge fund, before retiring in 2022. When you think of Ray Dalio, isn't he famous for his views on the changing world order?
Since he was someone who invested with the understanding that a nation could go through the cycle of destruction and destruction over centuries of history, even after retiring and stepping back from active investment, he is still deeply concerned about the world. That is why he continues to express all sorts of worries in his columns, predicting how things might turn out.
Although he has retired, he has n't completely severed ties with the company. He currently maintains an advisory role. However, since Ray Dalio was the head of the firm for so long, his influence remains strong. There have been quite a few criticisms asking, "What is the difference between when Ray Dalio was there and when he wasn't?" and pointing out that the direction of the firm is exactly the same whether he was active or before his retirement.
Currently, they are intentionally keeping their distance. Ray Dalio himself emphasizes whenever he writes a column that these are not Bridgewater's opinions, and Bridgewater also claims that these are their own independent views. However, considering how quickly ties are severed overnight, you can view Ray Dalio and Churt's opinions as still being remarkably similar.
Regarding today's content, I referenced two sources. First, I consulted a recent column by Ray Dalio regarding how U.S. domestic and international politics would change once the Trump administration took office. Second, since the new appointee is succeeding Dalio, I referenced an interview he gave on Yau Finance to create today's material.
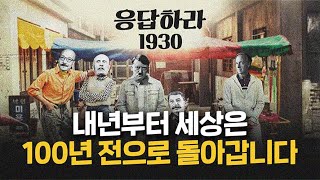
So, the main point today is this: the world is going to return to what it was 100 years ago. 100 years ago refers to the 1920s and 30s, and the future will become very similar to that era. He argues that the current situation bears a striking resemblance to the strong influence of nationalism, protectionism, and state control seen during that time.
Therefore, if the world becomes similar to the 1930s, the future of the United States... We also discussed the situation regarding stocks. And since we are returning to the 1930s starting next year, the world order is set to undergo significant changes; we even identified promising investment opportunities under this changing global order.
So, everyone keeps mentioning the 1930s, but what exactly was that era? Should we call it a decade of hardship? I think it could be considered one of the most difficult periods in human history. The Great Depression erupted in the United States in 1929, and the entire world suffered from an economic recession in its aftermath.
As the economy worsened, fascism resurfaced. A prime example is Nazi Germany, led by Hitler, where they began to seize power. Beyond Germany, fascism also began to emerge in Japan and Italy, and other nations started engaging in tariff wars while advocating for national protectionism. Then, with the outbreak of World War II in 1939, the 1930s...
So, looking at in what ways the upcoming era is similar to the 1930s, first of all, it means that nationalism is returning, just like in the 1930s. As I mentioned earlier, a form of nationalism that prioritizes national interests and places state power at the very top began to gain dominance during that period.
Representative figures include Hitler, Stalin, Mussolini, and Japanese militarism, are n't they? Likewise, the situation is similar now. Even before Trump's election, if we look at Europe, concerns about extreme nationalism becoming dominant persisted. Consequently, extreme political parties are currently gaining significant power in Germany, France, and Italy.
So, while this trend existed previously, the argument is that this trend will be further strengthened with Trump's inauguration. Dalio is not saying that Trump is a fascist or anything like that by saying the current era is similar to the 1930s; rather, he is saying that we will see a form of nationalism that blatantly prioritizes national interests and places the utmost importance on state power.
Now, if such nationalism that prioritizes national interests gains dominance, naturally, the government will become enormous They will seize power, and thus, the shift from the government to the private sector leads to the rise of state control; Trump is also exhibiting this tendency. Among Trump's campaign promises is the pledge to dismantle the "Deep State." So, what is the Deep State?
You know how we talk about "appointed public officials" and "career public officials"? Appointed public officials mainly refer to civil servants appointed to public service positions when a new administration takes office, while career public officials refer to those who continue their careers as civil servants regardless of the administration.
You can view the " Deep State" that Trump speaks of as a kind of career public official group. In the case of the U.S., administrations last from as short as four years to as long as [year], right? While administrations are temporary, career civil servants are usually considered to have "iron rice bowls"—meaning they hold their positions forever.
Since administrations come and go while career civil servants remain in office forever, they have become a kind of vested interest group. Therefore, they are seen as a kind of entrenched evil group that maintains the shadow of the state. That is why Trump has stated that he will implement a policy known as "Schedule F." What I mean is, regarding the cabinet members appointed by Trump, if these ministers schedule a specific public official, that official's position is not guaranteed.
In short, their "iron rice bowl" is being taken away, and they could be fired at any time. This implies that, in a sense, the power of the Trump administration is becoming immense. Therefore, in this respect, people are saying it bears a strong resemblance to the state-controlled administration of the past.
Furthermore, because Trump intends to push through the policies he has planned without restraint using this strengthened power, people are saying that, in this respect, it is somewhat similar to the 1930s. Yes, in the 1930s, as nationalism gained dominance and countries prioritized their own interests, they began imposing tariffs on one another.
A prime example is the Smoot-Hawley Tariff Act in the United States. This tariff is often cited as a cause of the Great Depression, and Trump is also openly stating that he will impose tariffs. But would other countries just sit idly by and take the tariffs imposed by the U.S.? Imposing tariffs against the U.S., or in addition to tariffs...
They will counter the U.S. in this manner while incurring a trade deficit. That is why this situation is quite similar to the 1930s. Now, given that these aspects are quite similar to the 1930s, what does that mean for the future of the U.S.? In short, it means that American-style isolationism will unfold.
We often say that if Trump is elected, the U.S. will go down the path of isolationism. Many people understand this path of isolationism as the U.S. turning a blind eye to the outside world and living only among itself. However, this is not that kind of complete isolationism; it is American-style isolationism.
It means that the U.S. will no longer act as the world's policeman based on justification or a cause. Instead, it will not get involved if it does not serve its interests, but will intervene blatantly if it does. So, what happens if this kind of American-style isolationism unfolds? Domestically, the U.S.
will enter a system of national power competition. Rather than things like diversity, polarization, or education, isn't the U.S.'s most important rival China? Since competing for national power with China is the biggest challenge, winning against China is considered the ultimate priority for the U.S.
But with China... To win the competition, technological capabilities must surpass China, and the economy must continue to grow. Therefore, they will likely try to stimulate the economy as much as possible by loosening regulations to support tech companies, lowering interest rates, and injecting funds into the economy.
So, people say that if Trump takes office, the US economy will be good and markets will rise. However, just because a system of national power-based economics is established does not mean that only economically efficient choices will be made. Since it is a system of national power competition, there are cases where they push ahead with measures if necessary for national security, even if they are not economically efficient.
A prime example is reshoring, isn't it? It would be ideal to build factories in cheap locations and produce cheaply there, but because production facilities are brought back to the US or near the US for security reasons, this is not an economically efficient approach. Furthermore, in the case of domestic manufacturing—specifically steel—the industry has lost price competitiveness compared to other countries, and as other domestic industries have grown larger, it has naturally declined.
However, because they cannot afford to lose manufacturing for security reasons, they have no choice but to make security-related choices, even if it is proportional to domestic manufacturing. And outside the US... International organizations will be neutralized. There are international bodies like the UN, right?
In reality, these organizations haven't had immense power. They have faced a lot of criticism that they are places that move according to the whims of great powers. However, because these international organizations exist, a certain sense of justification was necessary. People had to pretend to be moral and act cautiously.
But now, they intend to act blatantly without any of that. So, the US might not be a truly just world policeman anymore. They used to be cautious, but now they won't even be. Consequently, regarding competition with China, if there is a country that is essential to the US—for example, Taiwan must be incorporated into the US due to TSMC—it is predicted that the US will not hesitate to intervene in domestic affairs to ensure that the political and economic systems of such countries operate in a way that is most beneficial to the US.
So, let's assume that American-style isolationism is taking hold. The important question is, what will happen to the stock market going forward? First of all, it is predicted that the US economy will be fine for the time being. The market's thinking is that once Trump takes office, we will enter an era of high growth and high inflation to some extent.
It seems that this is the prevailing opinion. That is why, in the case of high growth, no one talks about a recession anymore, is it? Because the pattern of an economy deteriorating is that stores spend their earnings, but as the boom phase draws to a close, they borrow debt to fund consumption. Then, when interest rates rise, the debt burden intensifies, causing consumption to decrease and the economy to fall into a recession.
However, this time, because massive stimulus payments were made during COVID-19 and the US asset market rose tremendously, US stores did not feel the need to take on debt to consume. Also, since many people took out fixed-rate loans when interest rates were zero during the pandemic, they did not suffer a significant blow during the interest rate hike.
Another pattern of falling into a recession is a decrease in corporate investment. However, because AI is taking on the nature of a kind of arms race, companies are thinking, " Even if I don't make money from AI right now, if I don't invest in AI and fall behind in this competition, I will be left behind forever." So, because it takes on the character of an arms race, companies are reluctantly...
We have been semi-forced to continue investing in AI, and now that interest rates and the cycle have begun, I view the economy as continuing its growth phase. However, I expect prices to remain at a high level, as Trump's policies are bound to cause inflation. Immigration restrictions lead to labor shortages and thus wage increases, which is a significant factor stimulating inflation.
Tariffs also drive up import prices, contributing to inflation, and since the government will print money to boost economic growth, this is another factor stimulating inflation. However, inflation is manageable only when growth outpaces price increases; in a way, this can be seen as a risky gamble. This is because if the growth rate is faster than the rate of price increases, it is manageable.
But if the growth rate slows down even slightly and is caught up by inflation, then chaos ensues. Therefore, the Fed is aware of the extent of these risks, so it will not cut interest rates as boldly as it did in the past, as indicated by its dot plot. But fortunately... There is a risk of the market collapsing if it turns out that the Fed's massive interest rate cuts, which the market had been expecting, were not the case.
However, looking at various recent indicators, it seems the market already knows this. The market already understands that the Fed will not cut rates as decisively as suggested in the September FC's, so in this respect, it can be seen as somewhat fortunate. Furthermore, the Fed has stated that it will monitor how the tariff war unfolds when making interest rate decisions.
What this means is that if the U.S. imposes tariffs on a counterpart country, that country will not sit idly by. They will observe how prices react when considering the counterpart country's actions—whether it be imposing tariffs in return or taking other measures. They plan to watch whether prices rise temporarily due to tariffs and then stop, or whether the counterpart country takes action that causes prices to continue rising steadily, and reflect this in their interest rate decisions.
So, regarding how U.S. stocks will fare in this environment, to start with the conclusion, it seems there is still some room for them to move forward. I am discussing this, suggesting that it seems likely to rise further. The reason I brought up 1998 again is that this chart shows the US GDP growth rate, the S&P 500 index, and the benchmark interest rate at that time.
Regarding the situation back then, the economy was not bad; it was doing well. Stocks had already risen significantly since 1995, yet interest rates were cut. Consequently, stocks continued to rise, overcoming concerns that they could not go any higher. Then, they managed to stop the digital-com bubble and crashed.
So, considering the current atmosphere—where the economy is good, stock prices have already risen considerably, and interest rates are falling—I viewed it as having the potential to go further, even though prices have already risen a lot. Now, as I mentioned earlier, the rally ended due to the digital-com bubble.
So, does this mean the current trend will end with a bubble bursting? I stated that there are differences compared to the digital-com bubble. What I mean is that this chart shows the stock price and earnings per share of Nvidia, the leading stock in the AI boom. That is it. On the right, it shows the stock price and earnings per share of Cisco, the leading stock during the Doc.com bubble.
Did n't the stock prices of both Nvidia and Cisco rise frighteningly? However, the difference is that Nvidia's earnings continued to improve in proportion to the rise in its stock price, whereas Cisco did not. Although stock valuations are currently on the higher side, unlike during the Doc.com bubble, they are earning money just as well.
That is why I said that seems to be the difference from the Doc.com bubble. In short, I believe the probability of a bubble bursting absurdly like the Conn bubble is low. Now, regarding the question of whether I am saying to invest more if US stocks are good, I said that it does not seem like a good time to increase stock weighting.
This is because, as we saw earlier, they have already risen significantly, and while they are expected to rise further, the extent of that increase does not seem very large. However, the valuation is quite burdensome, and given past events like the Doc.com bubble, there is certainly risk involved. Considering these factors, the risk-to-reward ratio is not good, so I suggested that instead of buying more stocks right now, we should turn our attention to diversified investment.
Brit Sutter has mentioned this, particularly regarding the U.S., noting that both institutions and individuals hold a very high proportion of stocks in their portfolios. The graph is based on a survey conducted by Bank of America among fund managers; a negative light-blue bar indicates that one holds fewer U.S.
stocks, while a positive value indicates that one holds more, meaning the proportion of U.S. stocks is high. If you look at the graph, the proportion of U.S. stocks held by institutions began to increase from mid-to-late 2023. Although the proportion gradually decreased ahead of the election, these institutions are still answering that they hold a significant amount of U.S.
stocks. The dark blue bar represents the ratio of U.S. stocks to stocks from other overseas countries. The higher the value, the more U.S. stocks are held compared to overseas stocks; currently, institutions are answering that they hold an all-time high amount of U.S. stocks compared to overseas stocks.
Therefore, considering these factors, diversification is necessary. However, regarding stocks, overseas stocks seem to be a better choice than U.S. stocks. This is because expectations for U.S. stocks are already too high. Since earnings have consistently been strong, expectations are... The expectations are too high.
Looking at recent earnings announcements, one notable phenomenon is that even if a company delivers an earnings surprise, if they present poor future guidance, the stock price often plummets. This illustrates just how high expectations are for US stocks, making it difficult to meet those expectations.
Consequently, returns on US stocks may not be very high next year. Conversely, considering that countries with weaker economies and lower returns than the US have significantly lower expectations, I suggested that their stocks could actually perform well next year. I selected the "Global South" for these countries.
"Global South" typically refers to developing nations in Southeast Asia, Africa, and South America. One of the reasons for selecting this region is that it could become a beneficiary of the US-China conflict. Among these countries, those that are financially sound, have robust domestic markets, and have low dependence on or are not skewed toward either side are unlikely to suffer significant damage from the conflict.
Therefore, even if the US-China conflict causes problems in international trade, they are unlikely to suffer major losses. Because they are financially sound and have robust domestic markets, and since they do not have an unilaterally high dependence on either the US or China, these countries will offer significant benefits to win over nations that are positioned as neutral.
Therefore, I stated that global South countries meeting these conditions would perform quite well. That is why Darley has been heavily promoting India since 2022. While everyone says otherwise, Darley has actually been pushing India strongly since 2022. He believes that because the outlook for the US and China has worsened due to the US-China conflict, India will perform significantly better.
Darley uses a National Power Index to assess national strength and future growth potential every year, and he gave India the highest future growth forecast. Furthermore, he noted that ASEAN countries, some Middle Eastern nations, and countries like the UAE are in a similar trajectory to India. He suggested that just as India is doing well, these other countries could also perform well.
So, if the conclusion was to shift your stock investment focus from being solely on US stocks to emerging markets, then... Regarding what should be done at the asset class level, people are saying that the era of blind investing—such as the so- called 60/40 split of 60 stocks to 40 bonds— seems to be over.
This is because bonds are no longer what they used to be. People are now thinking that bonds are somewhat less attractive because they believe there will be no more zero interest rates in the future and that rates will not be lowered drastically. Therefore, the complementary nature where stocks perform well and bonds underperform when the economy is good, but stocks perform poorly and bonds do well when the economy deteriorates, is not expected to be realized.
So, if the outlook is negative, we must consider whether it is due to low growth or high inflation. If the downturn is due to low growth, increasing the bond weighting will naturally be helpful. However, if the downturn is due to high inflation, increasing the bond weighting is of no help at all. This is because bonds get crushed when inflation hits, and if you are worried about prices, holding a high proportion of bonds is not advisable.
So, in this context... We usually say that high bond yields are bad for stocks, specifically growth and tech stocks. However, it is no longer the case that high bond yields automatically mean these stocks will be bad. As I mentioned earlier, the Trump era was characterized by high growth and high prices.
Therefore, even if inflation is expected to be high, if the expectation that growth will outpace inflation is reflected in bond yields, then high bond yields will not have a negative impact on stocks. In short, if inflation is high but economic growth is expected to continue, stocks will not be affected simply because bond yields are high.
Of course, if the environment is one where inflation is high but growth is lagging, then high bond yields will naturally affect stocks. Therefore, considering the nature of bonds, it is said that they are at a crossroads where they must choose between them and gold. So, if you fear low growth, bonds are a better choice than bonds; if you fear inflation, gold is a better choice.
Furthermore, gold appears more promising than bonds because the myth that the dollar is an absolute safe haven asset has been shattered. Now, with tax evasion and the US-China If the conflict intensifies, the dollar will no longer be a safe haven asset for countries on the opposing side of the U.S., meaning the situation will be worse than when the U.S.
led the world alone. In that scenario, people will likely turn to gold rather than the dollar. Gold is highly valued by both the U.S. and non-U.S. sides, and since the gold market is significantly smaller than the dollar market, it is expected to rebound once funds from the dollar market flow into the gold market.
Although gold has recently undergone a correction and is on a downward trend, I believe that as money from the dollar market moves into the gold market, gold will rise again. As for crude oil, I anticipate a range-bound supply and demand pattern. It seems unlikely that demand will increase or decrease drastically, nor is supply expected to rise significantly.
Therefore, I expect the current range to continue. However, given that Trump dislikes Iran, if he imposes sanctions on Iran's oil production and exports, I believe there is a slight upside risk that oil prices could surge due to this. So, from their perspective, right now... I mentioned that I intend to actively buy crude oil because oil prices are attractive.
So, to summarize today's discussion, in a word, it seems we can view this as either the start of a new game or an overtime round. In other words, the existing flow of globalization and the market's expectations of Trump have already been reflected in prices. The difference lies in whether things proceed exactly as the market expects upon Trump's inauguration, or whether he acts faster and more extremely than the market anticipates, leading countries in competition with the U.S.
to react even more violently than expected. If Trump's policies exceed market expectations and trigger a reaction to them, then the " Trump trade" is valid. Representative examples include U.S. stocks, strong dollar stocks, and tech stocks; these will naturally perform well. On the other hand, if the market assumes everything has already been priced in and there is nothing more to be surprised about, then the current trend will simply continue.
Instead of continuing the current trend, assets that have been undervalued—such as emerging market stocks—will rise again. It can be viewed that way. However, in this current trend, aren't gold and Bitcoin a winning hand? Whether it's the start of the color game or overtime, they can be seen as favorable in either direction.
This is because, according to Darley and Bridgewater, the flow of the post-world movement continues, and as this continues, money will flow from the dollar to gold, so gold will continue to be good. Similarly, is n't Bitcoin good in a similar context? Also, Bitcoin is a newly born asset that has just been incorporated into the institutional system, is n't it?
Therefore, it can be seen as still being in its growth phase. So, ca n't these two be considered a winning hand? If we follow the logic of Ray Darley and Bridgewater, I think we can summarize it like this. Thank you for enduring this long video today. I will see you again with a better video next time. Please subscribe and like, and thank you for watching.


Comments 0