원문 보기
Bitcoin is falling again and most people assume it's just another dip. But this bearish thesis presented by Michael Bur argues something much darker. Bitcoin isn't just dropping. It could be entering a death spiral. And the reason has nothing to do with technology. It has to do with forced selling, liquidity traps, and the fact that Bitcoin may not have a real flaw anymore.
It's worth paying attention to because whether you're bullish or bearish, uh this is one of the strongest negative cases for Bitcoin right now. The main claim is simple. Bitcoin is not behaving like digital gold. It's behaving like a speculative risk asset. For years, Bitcoin's biggest promise was simple.
that it's digital gold, a hedge against currency debasement. But gold has thousands of years of monetary and industrial use and is used by central banks. Bitcoin's use has largely been narrative and flows. And when flows reverse, there's not much holding it up. Here's the part most people don't like to talk about.
For years, Bitcoin had an unspoken utility, illicit trade. But law enforcement has become dramatically better at analyzing Bitcoin's public ledger. And as that happens, Bitcoin's share of illicit activity declines. Bitcoin also isn't ideal for high-speed criminal use. It's slow, traceable, and increasingly risky.
So, this thesis argues that Bitcoin lost a hidden source of baseline demand, meaning a flaw quietly disappeared. Bitcoin bulls point to merchant adoption. Charities, businesses accepting Bitcoin. But there's a paradox. When Bitcoin rises, people don't want to spend it. They hoard it. When Bitcoin falls, merchants don't want to accept it.
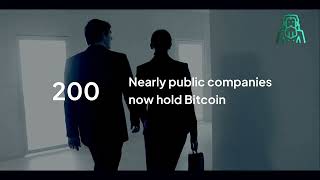
They don't want volatility. So rising prices kill spending and falling prices kill adoption. Either way, Bitcoin struggles to function as real money. Now bulls say corporate treasuries are the new floor. The excerpt claims nearly 200 public companies now hold Bitcoin. But here's the bearish counter.
Treasury assets are not permanent. Treasury assets must be marked to market. So when Bitcoin drops, those losses show up in reporting. And once losses grow, risk managers pressure companies to sell. Comes the biggest shift of all. Spot Bitcoin ETFs. People assume ETFs stabilize Bitcoin. But this argument says they do the opposite.
They make Bitcoin easier than ever to speculate on, and they make Bitcoin trade more like an equity. that increases correlation with the stock market. The excerpt claims Bitcoin's correlation with the S&P 500 lately has approached papi. That's not a hedge, that's a risk asset. Now, we get to the danger zone.
The excerpt suggests the average corporate treasury cost basis is around $80,000 and the average spot ETF cost basis is around $84,000. So if Bitcoin drops below where institutions bought, losses spread and risk mitigation kicks in. The excerpt points to evidence. Black Rockck's Bitcoin ETF, IBIT, reportedly hit a record single day outflow of about $528 million.
It also claims institutions liquidated over a billion dollars worth of Bitcoin across three straight days. Then the leverage side. On January 29th, the excerpt claims cryptowide liquidations hit 1.75 billion bars with up to 95% being long positions and in a 48hour window. It says 270,000 traders were liquidated with $2.5 billion in leverage Bitcoin wiped out.
Here's the key conclusion. ETFs aren't a stabilizing force. They may be the new panic button. Because when the biggest ETF holders reverse flows, the selling hits instantly. And the excerpt warns about concentration in a few major funds. So, the bearish thesis is blunt. Bitcoin lost a black market flaw.
Merchant adoption doesn't create real velocity. Corporate treasuries aren't permanent holders. ETFs increase speculation and correlation, and leverage turns sell-offs into cascades. That's why this argument says Bitcoin is exposed not as digital gold, but as a speculative asset, vulnerable to a self-reinforcing sell-off.




Comments 0