저자: 미상 · 외국인
요약 보기
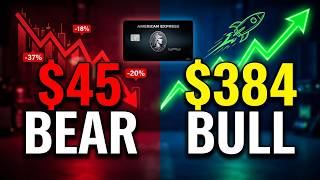
AXP(아메리칸익스프레스)는 기본가치 중간값($107.32) 대비 주가($324.43)가 약 202% 프리미엄으로 거래되어 전통적 밸류에이션 모델로는 설명이 어렵다고 설명. 은행 구조상 DCF·FCFF 등 일반 기업 모델이 부적합하며, 11개 유효 모델의 목표가가 $30~$384로 크게 갈림. 약세 시나리오 약 $45, 강세 시나리오 약 $343. 시장 프리미엄은 브랜드력과 실행력 등 모델이 반영하지 못하는 요소로 해석. 신뢰도는 낮음으로 평가.
다듬은 글
Welcome to this explainer everyone. Today we're unraveling a massive, honestly pretty fascinating financial puzzle regarding American Express. You know, calculating the true value of a company often feels like trying to hit a moving target. But with American Express, AXP, we aren't just looking at a moving target.
We're looking at a complete structural anomaly that literally breaks standard valuation models. So, let's dive right into this. We're kicking things off with a completely shocking number, plus 202.3%. According to a recent comprehensive valuation synthesis, American Express currently trades at a massive 202% premium over its calculated base valuation midpoint.
I mean, that is just a staggering figure. It immediately begs the question, what on earth is going on here? And this right here perfectly illustrates our core mystery. It's a massive disconnect. On one hand, you have market reality, a real-world trading price sitting pretty at $324.43. But on the other side, mathematical theory, a clinical model-derived base midpoint all the way down at just $107.32.
That is an absolute chasm. To figure out why this huge gap exists, we really have to look at the tools being used to measure it. That brings us to section one, why banks break models, or basically tossing out the standard financial playbook. Before we can solve this whole overvaluation mystery, we have to understand why valuing a massive financial institution like AXP is notoriously incredibly difficult.
Just look at this massive discard pile. When Amwal Invest first lifted American Express, they had to throw out almost all the standard corporate math models. Discounted cash flow, gone. Free cash flow to firm, tossed out. They scrapped leveraged buyout hurdles, Graham net net calculations, and even sum-of-the-parts enterprise valuations.
None of the usual stuff actually works here. So, the crucial point is that AXP's bank structure breaks these models because debt and customer deposits are the actual lifeblood of their operations. For a normal everyday company, debt is just how you finance things, right? But for regulated bank, deposits and debt are essentially their inventory.
Because of this, standard enterprise metrics, things that rely on physical asset replacement or standard operating profits, they're completely inapplicable to a financial balance sheet. Okay, moving to section two, the base valuation math, where we construct the composite from surviving models. With the standard tools rendered totally useless, we have to investigate the models that actually do work to build our baseline valuation.
Now, what's super interesting about how this composite methodology is built is the strict split it uses. It relies 60% on fundamental intrinsic value and 40% on assets. But notice the 0%? It completely, intentionally ignores market benchmarks for the base calculation. The idea is to ignore how the rest of the market values peers to find the absolute purest intrinsic value.
But when you break that down, it reveals some drastic extremes across the categories. You have a dismal $45 asset-based target on the low end. The fundamental intrinsic target is healthier, sitting at about $148. But get this, if you factor in the market benchmarks, which remember, were excluded from the final base weight, that target rockets all the way up to over $220.
We are definitely starting to see why this valuation is so fractured. Which leads us perfectly into section three, the investigation, focusing on the extreme disagreement across active models. Let's pull out our magnifying glass and look really closely at the specific intrinsic targets generated by the 11 active models that survived.
Just look at this wild, wild spectrum. We have a rock-bottom floor of $30 based on bare-bones net asset value. Moving up, dividend and return on equity models suggest values between $70 and $203, which by the way still means the current stock price is way overvalued. But then, an astronomical jump. Using the Peter Lynch fair value model, the target hits nearly $384.
That model is practically screaming that the stock is undervalued. And that brings us to section four, bulls versus bears, the great valuation tug-of-war. With numbers literally flying everywhere, from 30 bucks to nearly 400 bucks, we have to frame this as a battle between the ultimate bear and bull scenarios.
To maintain some serious analytical rigor here and to make sure crazy outliers don't ruin the math, the report defines the bear and bull cases very specifically. They didn't just cherry-pick. The bear and bull targets are calculated as the exact median of the bottom third and the top third of these valid active models.
And this brilliant, precise methodology leaves us with a staggering tug-of-war. We have a clinical bear case at roughly $45, staring down a massive bull target of nearly $343. It's like we are looking at two entirely different companies. Let's break down exactly what's driving these two opposing viewpoints.
So, the bears, they lean heavily on physical assets and dividend payout models. Applying a target multiple to the price to tangible book gets you that $45 figure. Even if you use a two-stage dividend discount model or the H-model, you only get up to about 65 or 70 bucks. The bears firmly absolutely conclude that based on what American Express owns and pays out, the current price is severely overvalued.
But then, we have the opposing bull narrative. The bulls basically ignore the tangible book entirely and look straight at growth and cash flow. Projecting free cash flow to equity gets them to an intrinsic value of nearly $343. And if you use that Peter Lynch model, which factors in an aggressive 23.5% earnings growth rate, that value pushes all the way to almost $384.
The bulls argue the stock is actually cheap, provided you believe in their incredible growth trajectory. All right, section five, market premium versus reality. This is the climax of our explainer. How do we actually reconcile these wildly conflicting clinical models with real-world trading? Decoding this massive disconnect is absolutely crucial.
Because out in the real world, market intelligence is telling a story of absolute momentum. AXP is dominating. Reports highlight that American Express is essentially lapping the stock market. A huge piece of this puzzle is how they are enticing businesses, letting them earn a solid 2.95% yield on idle cash with zero monthly fees.
The market is pricing in this flawless execution and premium brand power. Things those strict asset-based models completely ignore. So, what's the ultimate takeaway? Because of this massive internal tug-of-war among the 11 working models, the final valuation confidence rating is officially forced down to low.
I mean, when your active models give you answers ranging from a bleak $30 to an exuberant $384, extreme model disagreement is literally the only logical conclusion. The math simply cannot agree with itself. Which leaves us with this final, genuinely thrilling question to ponder as you look at AXP's soaring stock price today.
When a stock trades at a 202% premium to its structural base value, is the market just acting wildly irrational? Or are standard banking valuation models simply too rigid and outdated to capture the true modern magic of American Express? Next time you swipe your card, you really have to wonder, are you holding a piece of plastic or an asset that financial models just haven't figured out how to price yet? Thanks for joining me on this explainer. See you next time.


Comments 0