원문 보기
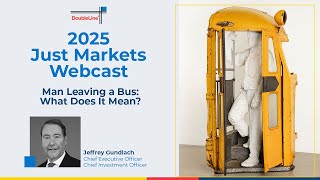
thank you operator and thanks everybody for joining us and welcome to the live from Los Angeles uh just markets 2025 webcast you'll notice on uh the slide on the screen right now I have a secondary title and that's man leaving a bus what does it mean and down there in the lower right is actually a sculpture by George seagull who was a fairly successful combination of Pop arts and kind of constructionist junk art back in the 60s and into the 70s and the reason I came up with this title which has turned out to be tremendously uh I I guess uh predictive in some good ways and some bad ways is I was I had this sculpture installed and uh somebody came over to my house and had been over a few times before but had never seen the sculpture before and in spite of all the various artwork I've collected over the years I have never once had somebody ask the question question that this person asked upon observing this sculpture by George seagull uh she actually said what does it mean I've never had anybody ask me what does it mean about art before and it's interesting that nobody ever looks at a Monae water lily painting and ask what does it mean in fact I've seen people uh look at artwork that's a pile of rocks and they don't ask what does it mean but interestingly I feel like this sculpture has a lot of meaning to it George seagull this was made in 1967 by George seagull who worked his Studio was in a used chicken Coupe it doesn't seem like protect it very much but I suppose he probably added some walls but George seagull is is best known for iconic life-sized PL plaster sculptures of people in ordinary settings critics repeatedly likened these uh plaster LIF side figures to fossilized pompe who were clossed by the lava FL from vvus so I came up with this title weeks before we had a wild fire problem in Southern California but it's uh interestingly predictive of of what's happening now seagull's works uh employ images of urban alienizer is often a political subtext as well seagull characters often sit sleep or stand in readily identifiable Urban settings but despite the familiarity of these diners gas stations and buses in American society the figures appear aloof and introspective seemingly distant from the viewer seagull's Works were often inspired by personal experience and seagull was a frequent commuter between New Jersey and New York and he emphasizes the themes of travel and people in transition the subject may be seen as an allegory for change or metamorphosis from one condition to another if you think about it specific to the bus in a in a bus you're in a group environment for a while you can share a space and an experience with a number of people you don't even know but then you're leaving the bus and you're leaving that experience you're heading out into more of loneliness and isolation and uh bus ride also bus is also figure into seagull's work because they are in contextualized in the political backdrop of bus riding boycotts in the Deep South uh sort of uh protesting the integration that was going on so the combination of urban loneliness with a realistic method of depiction places seagull in the same view vein of American realism as the great painter Edward Hopper in fact Mark Rothco called an early Seagle work he encountered as a walk-in Hopper a quote finally from seagull before we get started the strange thing about Modern Art is that it's not public art that celebrates the power of a king or a dictator it's it's an intimate reflection into the minds of ordinary people who are somehow valuable so I'll begin and we'll be working this through obviously I've been talking about change and transition for a long time I've titled it uh the fourth turning using the title of Neil how's book from the mid90s and I feel like we we're leaving the bus right here in the fourth turning just a reminder that uh last week after we had to evacuate from the palisad fire we had the very next day the filming of Roundtable Prime which has turned into a pretty uh important event I think industrywide where we have leading thought leaders it's the same group as last year Jim biano Dan Danielle de Martino Booth myself Charles Payne and uh David Rosenberg so we have a nice mix of people and as always it's hosted by uh Jeffrey Sherman our Deputy c c CIO and I thought this year we had a very good discussion I think one of the better ones perhaps it's because the group has been uh together now for a few years I'd really recommend uh taking a gander at this it's going to be up January 20th is the macroeconomic Outlook that's a inauguration day and then 22nd is just markets commentary and then on the 24th best ideas so let's begin with the bloodless verdict of 2024 where we see a variety of asset classes foreign domestic high quality and lower quality and what they did it's interesting that the S&P 00 was up 25% gold outperformed the S&P 500 up 27.5 gold actually was almost as high as the NASDAQ so it's an interesting combination that something that might be a store of safety like gold that I recommended a year ago uh basically held in there with the S&P 500 and the NASDAQ if you had a Barb portfolio of those stocks and gold you had one of your best years ever you see that uh risk assets in the United States did quite well when you look at translating back from foreign markets back into the US Dollars you see that Euro stocks were only up about 4.7 the nikai 8.7 Emerging Markets 8.0 so underperforming for dollar investors the US markets a lot of that had to do with the dollar uh going up went up substantially and we'll take a look at that then we see a fixed income category where there's not a lot going on the 10e had a negative return of 1.7% and the aggate index uh underperformed t- bills which a 1.3% return agency cnbs which is one of our uh our favorites entering 2024 was up seven and then the credit Market not surprisingly when stocks outperform bonds by a lot you can expect junk bonds to outperform treasuries and indeed that's the case with bank loans actually slightly outperforming fixed rate regular way high yield and EM Sovereign did pretty well up 7.0 thank mostly to the latter part of the year we see the Dixie the dollar Index which is is heavily Euro dominated up 7.1 and then we see all these other currencies versus the dollar down 6 to 11% and then Commodities it's really a story of gold uh really driving just about everything we don't have Bitcoin on here obviously Bitcoin I always characterized Bitcoin as gold on massive leverage and indeed uh Bitcoin was up a very large amount in fact since uh since a September uh uh uh 18th the first uh Fed rate uh cut Bitcoin was up 58% through yesterday so other Commodities that are important oil Brent down 3.1 and the agricultural Commodities also down this is the current valuation at least as of near the end of 2024 of various asset classes so uh at the x-axis that's the year of inception of all these different metrics evaluation so for the S&P 500 it's 1990 and we're at the just about the highest valuation ever and you can say that right across the S&P sectors with the exception of small cap which is more like 50 or 60% and midcap which is around 60% and then we get to the smaller caps they're overvalued as well uh but not as much and they go to non us equities and yes India looks overvalued uh I've been recommending India as a permanent hold and that's the only way I think about it I don't think about trading it I don't care that India is at a high valuation because of a tremendous demographic and geop political advantages that I see there for the long term then you get to fixed income and we see that going back to 1999 mortgage spreads to treasuries are cheap it's the only thing on this page uh that says that's really cheap historically then you go to corporate bonds they look just like equities where it be high yield uh investment grade corporate they look overvalued and then we see uh Triple C's a little less overvalued but still all these in the overv Valu category versus uh history of their own uh internal valuations except cmbs so it's basically mortgage related Securities that are cheap versus historical valuations and uh we have weightings that are well thought through of course let's take another slice at historical returns this is a quarter centuries going back to 1800 and you'll notice that uh in the gold lines so at the x-axis it's at various asset classes so equities over the last 25 years 7.6% 10-year treasury 3.9 uh t- bills 1.8 interestingly I'm switching up to Gold 9.5 the best performer is gold even outperforming equities for the past 25 years but don't forget those 25 years have a start date of 1999 which was a secular peak in the market with with tremendous pees tremendous enthusiasm for a technology of the Dooms very similar to our market today in terms of valuation and in terms of enthusiasm for a narrow sector which May ultimately be an excellent investment but uh as we'll see in a few slides might be a little bit overly exuberant at this time you know it's the worst performer on here is t- bills and you have Commodities the same as t- bills I really think over the long term Commodities and T Bills should have the same returns um Commodities are constantly under downward pressure due to increased technology and they're under upward pressure of at times due to demand but all in all Commodities really should not have a real rate of return I don't think they should with the advancement of Technologies so this is a long way looking back all right let's look at some uh uh recession indicators and some economic indicators I'd say one of the things that's different now that we're leaving the bus on is a lot of the things that we thought we knew and I talked about this in past webcast may have been informed by a secular environment that is changed for example secretly declining interest rates I believe have been replaced with at least at the long end secularly Rising interest rates so like with the man leaving the bus what does it mean that we're leaving the bus in some of these secular changes well some of the traditional recession indicators don't work haven't been working because they've worked during a different secular regime and we'll see in a several slides forward the copper gold ratio has stopped working completely um fed has been cutting rates what's different here fed has been cutting rates what does it mean well for the first time we see the long end going up with the FED cutting rates we'll talk about that more uh what else is going on that's different from the past well it's not different from the distant past but we have States talking about nullifying federal laws um that was In 1832 that South Carolina nullified some laws that were put on them from the federal government of course ultimately the ultimate nullification of federal law was the starting of the Civil War 30 years or so later uh We've also had a ridiculous uh media cover coverage of the presidential situation with a tremendous uh disagreement among commentators and and networks and media outlets on what really is going on who's running things what's the condition we also have the tightest spreads ever on uh corporate bonds we'll see that uh later in the presentation I say that has something to do with the budget deficit and the fear that people have that that similar to they had in the early 1980s uh where it was considered for a several year period that corporate bonds might be safer than treasury bonds given the expansion of the deficit which by today's standards looks absolutely trivial we also have something different with people leaving the bus in a different way and that is the 1940s the people that were born at the best possible time the Nancy Pelosi the Joe bidens the Mitch McConnells a lot of people I you can say the Warren Buffett these are people that were born where you just couldn't miss you know the United States was enter exiting World War II uh the productive economies around the world were decimated and we had this tremendous uh ownership of the industrial uh economy was hard hard to lose but those people are now disappearing from Power with Joe Biden out in under a week and some others that will soon should be uh stepping down as they're in their 80s or even in mid 80s we also what else is different is The Impossible debt trajectory which I had an article about and The Economist a few weeks ago how it cannot be sustained we cannot keep stacking up this debt what's changed is people are now aware of that to a greater extent finally and of course we have uh a massive growth therefore in interest expense so let's look at one of the recession indicators that may may not could be deemed as hasn't really worked yet anyway and that's the the yield curve the two 10 spread and its 12-month moving average is the darker gr blue line and we see that in historical periods when we went inverted with the red shaded area once it de inverted uh you were generally in a recession that at least on an official basis hasn't happened yet I I do wonder what the revisionists will say in future periods as to when Whatever Whenever this recession begins when it started the 36 uh month moving average uh the 12- month moving average rather line um really looks more like we're exiting recession or in the middle of a recession but anyway this one for now has not really worked another one that has not worked is the leading economic indicators I've talked about this in the past that this is mostly because we've had a handoff between the services and uh manufacturing economy that's been in play all the way going back to 2020 with the strange uh behavior of the federal government with all the money Printing and so forth and uh but we say the leading indicators have been negative forever we've never had leading indicators negative for three years and not have been uh deeply in recession but that's the case right now here's manufacturing pmis they're all over the place but we see the manufacturing pmis just it's not a coincidence that similar leading indicators because leading indicators have a lot of manufacturing in them but you'll see the services PMI is at a very large Divergence but no recession here's housing affordability it's to throw this in for completeness housing affordability is is terrible we had a brief moment last year where affordability went up thanks to Falling mortgage rates but interest rates have risen by over 100 basis points uh in the past just four months and so we see that affordability is near the low again and then one last thing about the economy that should be observed and carefully monitored is credit card writeoffs have risen pretty dramatically they're pretty far ahead now of where they were pre pandemic and the trend was bad pre pandemic it's almost like if you took that trend from 2015 and drew a line through 2019 we we had a moment of respit because of all the free money from the government no uh we didn't have we had people spending money but now they've uh don't have all that money from the government anymore and it's gone back to credit card spending we're starting to see those writeoffs that's something to look out for this is something interesting what's happened since say I'm going to say early October I would say is when it became fairly obvious that Trump was going to win some interesting things have happened since then um that is here's National nfib Small Business optimism index and it was headed straight down uh under Biden I'm sure some of that had to do with the lockdown the pandemic but it never recovered all the way through go Biden's Administration it was at Rock Bottom actually it hit Administration lows uh back there in the in the middle of 2024 and then all of a sudden people realize Trump's going to win and then he does and the thing skyrockets uh back up from you know maybe 87 up to 105 which is the most current reading uh this is I think people are just mapping 2016 2017 on to 2020 2021 we'll see if that works out but it is exactly the same behavior as the 2016 election it is interesting uh here's another one that's uh exploded higher this uh is also uh this is not quite the same but uh as the Trump thing this is instantaneous when Trump went in 2024 we uh households expecting their financial situation to improve and and consumer sentiment we don't have consumer sentiment yet it's not updated but here's the expecting financial situation to be much better or somewhat better in 12 months is the green line and it just it looks exactly like that um business op small business optimism so we we'll see if this has some follow through economically one of the reasons I think that people feel this way um that you know the that the the uh financial situation might improve is look at the yellow line we see that after Trump was elected we saw for a real increase in the median weekly pay for those with less than a high school diploma real gains there about a 20% gain and that stopped uh once Biden got in all remained at the same level and we see very uh some progress under Trump in advanced degree and bachelor's degree but nowhere near as much as lower than uh High School deployment and of course we see under Trump some college also everybody improved under Trump now maybe that's uh not not a cause and effect but it certainly is contemporary and we see now that we'll we'll be interesting to see if this if this continues to happen I suppose if it happens it's difficult to square that with lower inflation I mean higher wages and medium weekly pay would probably be go along with a higher inflation here's another Trump thing this is the last of well there's one more after this Trump thing so we see in October all of a sudden something happen and that is that the consensus forecast for GDP uh we have a a dispersion now we see that the one for Europe the Euro Zone deteriorated from consensus GDP of 2025 of4 it's gone down to 10 whereas us it's gone from two from 1.7 or so to 2.1 so it's interesting that that's happened now it's surprising really kind of given the strength of the dollar a little bit in that here's last one expectations of higher stock prices and this goes back a long way back nearly 40 nearly 40 years and we now see that maybe Trump had something to do with this but was already underway we see consumers expectations of higher stock prices were on a moonshot already and then really went to by far an all-time record I do not view this as bullish by the way um I think that expectations of higher stock prices against the context of today's valuations that I showed in the second slide are are pretty hard to deal with particularly because the Federal Reserve has gone from a very well the market has gone from a very aggressive Assumption of fed Cuts uh through the end of 2025 and now we're talking about one not even one and a half Cuts is the base case by the market so let's take a look at some fed things here's some developed developed Market rates policy rates and back before I don't know 20 16 we had some periods of time from 2020 to 2016 or so where some R some banks were cutting While others were hiking and that all went away a post pandemic we see these central banks with the one uh exception of Japan are basically all uh in in lock step with each other those that are hoping for or wishing for a global Central Bank it seems like since the lockdown uh they're getting their wish so so we're leaving the bus and the lockdowns and Co had something to do with that and we're entering into a period of perhaps greater disillusionment and loneliness here's fed funds versus the uh fed fund Futures and we see that the Gap has narrowed pretty substantially look at how big the Gap was back before the first cut in September the market the markets expectations were just kind of screaming for the FED to cut rates and so they had to get sync and they've done that uh we'll see that on this slide which is yearend 2025 forecasts versus the fed's uh forecast of me of pricing and we see that how far behind the Fed was before they started cutting now they've cut and they've met the market so the FED is now in sync with the market and the market has not been giving any signals and I I believe that's could be why the FED is slowing down because of course as I've said repeatedly the Fed follows the 2-year and this is further definitive proof of that fact here's the market pricing of cuts in 2025 we'll see at the first cut before the F before the first fed cut we were talking about 150 basis points of cuts in uh 2025 and now it's down to basically one or a little bit more than one for for 2025 this is one of the reasons why the stock market is not happy uh in recent weeks because they were relying on this big rate cut which of course is typically helpful but rate cuts are acting differently this is a chart that I think might be the chart of of of the year so far this is the tenure US Treasury performance around this is price performance around fed cutting cycles and this goes back to all the cutting Cycles since 1984 so we've got these bands we've got the the the tan thing is is the uh is the uh the h and the low and then we've got the 20 to 20 to 75th percentile is the dark area and the 10th to 90th percentile is the is the lighter blue area and the red line is this time so we' have never seen the 10-year treasury yield go up with the FED cutting rates and uh this time it's by a significant increment the worst before the worst before was the tene treasury by uh week uh by week 88 or SO trading days rather trading day 88 had basically treaded water that was the worst one before but this time since the first fed cut the tenure treasure rate since the day before the Fed rate cut is up 117 basis points so something is different this time and I think it has to do with what I've been talking about now for a couple of years that when the FED starts cutting rates you might be surpris that you don't you might get initial rally on the tenure before they cut rates I talked about but once they started cutting rates and you can see that that happened on here the price went from about 90 to 100 on the red line but once they started cutting rates it hasn't worked and so I think we're on to something here here's just charts of interest rates going back about 10 11 years and we see the two-year treasury peaked out at 522 uh it's really come back up with fed hikes fed cuts for being priced out see the 5-year treasury uh had a nice rally and it's now almost back to the highs about 40 basis points below the 10 treasury really seems to have broken to the upside again we had a little de trend line from the 499 yield back down to about 360 or so but now we're almost all the way back towards 5% and the 30-year Bond got to 511 at its high in October of 2023 but it got to 501 today so we're within spitting distance of the high uh of of 2023 in in the long Bond so here's the 10-year treas yield and the Dixie index and obviously for 2024 the movement in the dollar is entirely explained by the movement in the 10year treasury y you can see that they're they wiggle and jiggle exactly together it's not surprising because with us rates with this rate rise towering over a much lower rate rise in other Bond markets the uh B the dollar becomes more attractive as an investment and so money flows into the dollar we see here's the US tenant treasure yield and the Bloomberg economic surprise index and those that typically moves in the same direction not simultaneously but broadly speaking they go up and down together but suddenly that's broken down and that broke down pretty much uh since the FED started cutting interest rates uh or certainly the second rate cut so we see now that the economic surprise index is going down and the 10e treasure rate is going up this is one reason to think that the sell-off in the tenear treasury for the short term anyway might be overdone because this is a very wide Gap and directionally they're very different take a look at what was in May in 2024 we had a similar setup now didn't we but what happened is that the economic surprise index stayed weak and that it was no doubt somewhat encouraging for the 10-year treasury yield to drop we'll see if that happens certainly 10e treasury is a lot more attractive today than it was for months ago here's a 10-year treasury government bond yield versus China and I put this on just kind of fun facts to know and tell that the Chinese bonds 10 years for a decade yielded substantially more than the US tenure and that is completely reversed in the past four years with s with almost non-stop decline in the in the Chinese tenure and a very rapid uh significant rise in the US 10 years so we're now well over double the of the Chinese tenure of course this suggests that there's problems in China obviously that are likely to bleed over perhaps into other economies we'll see what happens with that one here's I said this earlier some things are not working the copper gold ratio is just not working it looked like maybe it was back in gear in 2021 2022 but not anymore we see the copper gold says that the 10-year treasury yeld should be about one and a half I think that with secularizing interest rates and has changed things and gold is not really being bought for the same reasons that it was in the past one thing that's changed is central banks have been buying gold very sub substantially for quite a few years now but that continues on with the uh ownership of gold at central banks being a supporter of the price and I think gold is being treated as safety by people uh certainly I feel that way safety from this bus that we've left not knowing exactly what sort of an environment that we're headed into and uh these wildfires which I'm not going to talk a lot about but these wildfires are very very uh significant I think they're much more significant Than People realize the the concept of rebuilding is not even a concept yet people talk about the process of rebuilding there is no process there is nothing organized nobody's in charge uh nobody prepared for this there I think Gavin Nome he said one thing that's great is is California's good at rebuilding one thing California's good at rebuilding they should be better at not needing rebuilding and I think the whole society in Southern California is feeling that way including a lot of people who were very supportive of many of the policies that at least in part contributed to the potential for these fires a lot of these people that were gung-ho for these policies are suddenly gung-ho against them and it'll be interesting to see if that uh has legs so that might be all on the Fire here's one thing that is working for the tenure at least directionally and that's crude oil West Texas intermediate crude and 10year treasury yields uh we can see that they have really been uh quite similar uh the 10year treasury yield here does look ahead uh kind of extended versus the crude oil price this kind of either suggests that oil might go above 85 which would be a problem for the FED in a big way or that maybe the yield is a little bit uh Beyond itself uh we'll see we can we continue at Double L to not be a big fan secularly of long-term treasuries I I wouldn't be surprised to see a shorter term uh reverse rally for some period of time on the 10year treasury so we have not we we remain underexposed there but we are not really a seller of longer term treasury bonds at this level it's just bad trade location and here's one uh we talked about China and the US tenure isn't that interesting Japan even yields more than the Chinese tenure Japan the lowest yielder in the world forever for decades now yields more than the world's second largest economy uh China very interesting let's get to inflation and some fed ideas I'd start with this because this is the fed's uh leading their favorite indicator so they say it's the pce deflator and the core PC deflator and one thing that's got the FED a little bit skittish and J Powell was kind of all over the place at the most recent press conference he's seems to be understanding that there's a growing tension between the so-called dual mandate it looked like they were in a good spot with the inflation part of the Mandate since I don't know may of this year and then we're starting to see some reversals on the pce flattening out and most uh recent data points going up I don't think this is an alarming level certainly 1.89 headline is not alarming but the core level that they have kind of boxed themselves into favoring uh repeatedly over time is at 2.4 and it's no longer falling uh here's CPI which is still higher than the FED supposedly wants we see the headline at 2.7 most recent tick was not down and we see the head the core number at 3.3 and it's stalled out at a level it's really too high for the fed's of commitment which is strongly stated emphatically stated over and over at every single fed press conference that they're trying to get to two so 33 is not two here's producer prices this is no doubt also worrying the FED it was great back in middle 2023 when we had the headline down at almost zero but now it's interesting core and headline PPI are exactly the same if they're at 3.31 and that's exactly the same as what we saw in the previous slide which is the core CPI also at 3.3 so this is too high for the FED that is uh keeps chanting the Mantra of we are committed to 2% inflation and obviously the direction of the headline is pretty bad on this chart and if oil goes higher which it has done lately uh this could be a further uh problem for the fed's desires to maybe not raise not uh not stop cutting interest rates at all during 2025 now one thing you can look at if you really want to slice of the baloney a little thin you can take core CPX shelter which is getting you down to to a pretty small fraction what people actually are exposed to inflation wise but if you do of course Epi ex shelter you're down at the 2% sort of a level so maybe the FED has something to cling to with these Trends not being as favorable as they'd like in the other things here's just a stacked bar chart of what is the contributions to core CPI obviously shelter is a huge piece of it uh you know more than half of the of the core CPI is shelter and then we see core Services X shelter is much smaller smaller than the blue bars but inflation is entirely core so one thing that the fed's hoping for so since shelter is such a big piece of it they're hoping that the Oar the blue line and the CPI can continue to gently come down we have the Zillow rent index on here uh and we've got it with a 12-month lead versus The Oar and while the rent index is no longer declining it has settled in at a pre-pandemic level and so maybe the Blue Line could go back to a pre-pandemic level that's that's the one thing for the FED to really hope for I think to get to not have to put rate cuts on hold or to stay where the markets as they're going to say because it's been harmful to uh the psychology of risk assets here's uh month the CPI month over Monon change and this is what has got the FED zigzagging uh I said back when they started uh uh cut hiking rates back when they were behind the curve on the hike I said the FED looks like Mr Meo driving around nearsighted bumping into things and not really having any Vision um and then you know we we got out of Mr migu they went into a systematic sort of disciplined process and inflation has at least made it down to the mid tws or 3es they were pretty happy uh back in the first part of 2024 because the headline CPI month over month was in a three-month four-month declining Trend and actually got a negative number back at the middle of the year but uh unfortunately you see that for the past 5 months this is an a rising Trend so the CPI comes out uh tomorrow I believe it is when it comes out we'll see if we get yet another increase I I believe this is why the FED has gotten into this back to this Mr meu short-termism they they need I would I would really love to see the FED get back to more of a strategic plan than there I I would say that they're over short-term data dependent at this point in time but the one thing I like the best oh here's here's a this this one this was headline CPI here's core month over month same picture same exact commentary they now have kind of six months here on the core CPI that's just too high at at a 3.1 type of number you're in the high 3es if you annualize that uh for a full year what what you do what you can uh be comfortable with on inflation is my favorite inflation series export and import import prices which have stabilized at about 1% so not a lot there one thing that the FED can probably like is that the quit rate continues to fall they don't probably don't like that for one part of their mandate the employment side which we're going to get to starting now but they might like it for the inflation side because using this lag with the ECI and the quits rate we see that uh uh based upon this predictor it's a one variable predictor so be take that for what it's worth but it's down a 2.1 would be the projection for where this might be nine months from now it's not a perfect fit but there's a lot of directionality certainly that correlates on this chart all right here's the twoos 10 and the unemployment rate so the yield curve so the when you're below zero you you have an inverted you you have a the tan line is the uh unemp rate the blue line is the two yield curve and below zero on the blue line you're inverted you can see there's a pretty good uh fit here that the unemployment rate going up tends to lead to the 210s de inverting or vice versa or maybe it's just simultaneous what we see here is the unemployment rate using this fit I don't know it look it's it it ticked down in the most recent data but again with this all this immigration with all these people entering the labor force through uh illegal illegal immigration what we see is that we the Labor Statistics are screwed up we thought we were in a bus with a certain set of circumstances and people but now we have a totally different Baseline in terms of the workforce and what levels that Workforce can operate in terms of skill and where they're located but just simply based on this one would expect the unemployment rate to go up but this may not work uh with this secular shift in things and here's that 36-month moving average of that employment rate which like the S Rule and it's kind of similar to the S rule although we created it before I had heard of the S rule we have what we have here is a a barely a recession trigger signal back in the middle of 2024 but uh we haven't really maintained we're now exactly on to be literal about it I think we're one basis one basis point below the moving average of the uh unemployment rate but this is this recession signal hasn't really quite triggered yet we'll see but here's just the unemployment rate backup versus recession similar that thing I did on the FED cut starting to cut rates and the 10year treasury movement here we see the median over going back to all the recessions over the past you know decades uh and uh we see that the median of all that is the unemployment rate starts to rise and it's horizontal the S the vertical line at zero uh shows when the recession officially started per the BLS and then we see where the red line is where we are now so it looked like we were maybe starting a recession say four months ago now you might argue that the red line should be positioned perhaps a little bit further to the left nonetheless whether however you position it it does have something of the look of the median movement in the shape of the unemployment rate moving in Prior prior to during last recessions here is something the fed's looking at I put this on because this is a Fed section J Powell is talking about the labor market being in Balance what he means by that is that that sha blue shaded area down at the bottom looks like it did in 2018 19 and 20 when the labor market was thought to be imbalance we've come back to that situation so I think he's happy with this chart Jay is I think he's probably happy with the preceding couple of charts that the unemployment rate has stalled out at about 4.1 even though it's still in a rising R Trend reminiscent of recessions so so he's that what what he likes I'm sure he doesn't like this one and no nobody should like this one I've used this many times before we have the unemployment rate is the dotted line uh here and then we see the red shade area which is the budget deficit as a percentage of GDP and we're going to see a slide in a moment but you your eye can see that when you're in recessions before them usually you're at a good place at least relative to historical context on the deficit as a percentage of GDP but this time we're very high we're recessionary levels of the deficit and the official deficit is now about 6 and a half% maybe seven of GDP but it doesn't include the aid to Ukraine it doesn't include natural disaster relief which is always viewed to be temporary but man if you thought the naal disaster Master relief for the past 12 months was high which you see what comes in the aftermath of what's Happening uh nearby here so there's a lot of room for that uh deficit to go up if and when the unemployment rate goes up during a recession and here's a scatter plot going back to 1960 on the x- axis is the unemployment rate and then on the y- AIS is the budget deficit as their percentage of GDP and if you do a fit from 1960 to 2017 that's that line you'll notice that we're way out of the context we should have a to we should have a budget deficit which is now really at 7 and I well let's make the data consistent so we'll say that this is seven it should really be at more like zero as a percentage of GDP if you if you go back all the way to 1960 I'm sure a lot of these zero dots were prior to 1985 and so we have a different look but if we just use this entire time window 2060 not 1960 to 17 the deficit should be uh something like 7% lower than it is now so that's pretty bad but during recessions as we know the the deficit goes up as a percent of GDP back in the old days it was about 3% of GDP in more recent times it's been 99.4% of GDP God forbid if we can eliminate covid uh then we would have an average of more like 7% of GDP that would take us up to 14% of GDP and if we want to Discount the global financial crisis you know one thing I like about J Powell is he says if you throw out the data you don't like you're really not getting a clean view of a survey of the landscape and I I like the fact that he understands that but if you take out the most recent two and you go all the way back to 01 then it's 6% okay so we'd be going up to 13 14% of GDP uh which is just outrageous given a 37 trillion is doll uh of national debt so at a 5% interest rate which we might be closing in on on the long end and maybe we're stalled out at four and 38 on the short end let's say let's just use a round number and say it's 5% I mean if you go to Just 10% of GDP you'd be talking about let's just say a little higher than 10 you go to you'd go to you know a a four 44 trillion deficit and you'd be looking at a an interest expense when it fully rolls over that's pretty horrifying as as a percentage of of budget Revenue in fact this is the federal interest expense as a percentage of federal tax revenue which is going straight vertical uh of course this is going higher of course the CBO projections are optimistic they assume interest rates lower than where they are today they assume deficits lower than they are even today and they assume no recession ever which I can't blame them for that little hook down is the is may not happen that's the tax cuts expiring uh but now that Trump's won maybe they they won't they won't expire and that would just mean that the dod line would continue a pace and we would be up very quickly to about 30% I'm using numbers that are not consistent with Y access because I've done more risk realistic analysis than the CBO but we'll be up to about a third uh under certain policy assumptions of tax revenue going to uh interest expense payment a third of all revenue and I think we can all agree that that has really dire ramifications and of course the Trump Administration is talking about cutting taxes so if we're going to cut taxes uh and we're not cutting the deficit it's a kind of an interesting combination it's kind of a combination of overdevelopment not cutting back the brush and uh not funding uh uh safety and prevention as priorities in your state budget uh allocation let's go on to equity S&P 500 with its moving averages we got uh to one of the most overv uh in history versus moving averages this only goes back to 2016 but this was kind of the same view of 2021 in my just Markus webcast three years ago I talked about how greatly overv the equity Market was but then I added that it's very cheap to bonds that was actually well below average versus the 10-year Treasury and lo and behold 22 was a terrible year for bonds it was a bad bad year for the S&P 500 but the S&P did better than the 10 year during 2022 I don't think that's the setup uh that we did at the top here at 6,100 on the S&P because the reason that the S&P was so was cheap versus bonds three years ago was the bond yield was at one now the bond yields at five and the S&P 500 is about the same valuation we saw that on one of the first slides that were very overvalued versus history going back to 1990 we were obviously very stretched versus the moving averages and and when you have uh consumers looking for Monumental gains in stocks from that type of 6100 level uh you you've got uh the recipe for at at at at least a significant pullback which I believe is is presently underway now let's look at just some some cross sector valuations the S&P 500 is in something of a world of its own it's outperformed equal weighted by from a from a by by about 40% or so uh since uh 2023 and now we have a double top so this would be a good entry point for equal weight I believe versus Market weight here's growth versus value same commentary this is a good entry point for Value versus growth uh this I know that that's a little bit impaired by the FED slowdown of their cutting cycle but that's probably why we saw this uh Resurgence and growth versus value in recent several weeks or a couple of months us activities versus the rest of the world it's just non-stop I mean this goes back this goes back seven years but really you could go back 20 years you have the same thing this one is not a double top and this probably won't work until the dollar tops out and if you're looking for a reversal here which clearly hasn't happened but look at this one this is incredible stocks versus the rest of the of the world um just us stock versus global xus indices and we're totally out of the context of any other situation um you know we had we had bubbles over certain time periods we interestingly we didn't have one in US equities versus non- US equities going in the global financial crisis that had to do with the relative um movement in the financial sectors of the US markets versus other markets but now we're just ridiculously off the charts versus history that doesn't mean it can't this can't get more extended because for this to reverse I really do think you need the dollar to top out so we're going to talk about that uh in in a little bit here's the S&P versus Emerging Markets uh same story but even more uh extreme than just the broadly the rest of the world we see Emerging Markets have underperformed the S&P by a factor of over 100% since 2015 and you could take back to 20 uh further than that to 2010 and it would look even more severe so we're very highly valued here Emerging Markets continue to underperform on a dollar basis you need the dollar to reverse so here's kind of the proof statement of that this is S&P 500 versus Emerging Markets compared to the trade weighted dollar and while they don't line up exactly it's pretty obvious that eer that S&P outperforms when the dollar is going up and it underperforms uh when it when you're going down which there's only one s long-term example of that out here but it worked almost exactly so you need the dollar to top out so let's take a look at the dollar here's the dollar Index we next to 1970 and one thing I notice is that we're we've been in a secular decline in the dollar but since the global financial crisis we've been in a reversal the dollar has been strengthening irregularly but strengthening I notice if you draw a trend line from the 165 level back in the 80s to the level in reached a couple years ago which was around 115 or so if you drew a trend line through there or right on it at this 109 and a half level nearly 110 level we're right on that trend line be interesting to see if we break above that trend line it would actually be something of of an event so I'm I'm watching for that pretty carefully um I I I'm kind of agnostic as to whether it will happen but the dollar Index uh looks to me like it's not quite topped out yet but we're on that trend line here's uh more recently so we can see just how violent this up move has been in the dollar this could be a trump thing as well this goes along with those other Trump moonshots they all started at the same time uh around the late September that is also around the FED cutting interestingly that with the FED cutting that the dollar started going up so perhaps you think it might be the opposite but as I showed on that that chart that we have almost a global Central Bank a lot of central banks have been cutting somewhat in lock step so I guess that means that the maybe the Trump effect has more to do with this than uh the the FED because it's been in lock step this is the dollar versus Commodities this is interesting because the the commodity index is actually start looking to be sideways it's helding up holding up pretty well with the dollar going up so much you typically expect Commodities the tan line to be following but that has not happened so it's it's that's interesting because this correlation is very very convincing and we have this big Divergence does this mean that the dollar is about I I I'm not really sure I want to predict which way it's going to go I'd say an interesting pair trade though would be you know short the dollar and uh and uh short the Commodities here's the Bloomer commodity index versus 200 day moving average we see after living below the 200 day moving average for about a year year and a half kind of broken above and the 200 day moving average is is bottoming out as well so this is an interesting time for Commodities I I find this move to be surprising given that the dollar has been so strong here's gold which we liked a lot at the beginning of 2024 it did better than what we expected with a 60% you know 30% gain on the year and uh all went all the way up to 2,800 it's it's consolidating right now is gold and I think it'll have after this consolidation I think gold will probably have another move higher unless unless uh the dollar goes much much higher I talked about why gold is going up and I talked about central banks here's IMF World Reserve gold Holdings and we can say that they stopped they went way down from 1990 into the global financial crisis and ever since then they've been rising kind of non-stop at almost exactly the pace that they were being sold off at so very substantial Trend change let's talk about fixed income uh and then uh I think we'll kind of wrap it up we have here uh yields across fixed income sectors so we have the diamonds were the end of 2023 and the blue bars are the end of 2024 so we had yields on treasuries go up a little bit in 2024 you can see that on the Le hand side that's just the treasury index broadly we see yields on mortgages went up a little bit more than on treasuries the blue bar is above the diamond uh credit yields even went up a little bit so yields across the investment grade category went up but we see yields on high yield bonds did not go up because the the yield rise on treasuries was matched by a spread tightening on high yields so the yields are the same uh pretty much pretty much same for double b single B it's exactly the same we see single Triple C yields are down so yield spreads tighten a lot just like stocks went up a lot that would be highly correlated then we see no change leverage loans or double BS or single B's and leverage loans uh then down the line we see cmbs yields came down and so forth but now we're seeing that you can get yields pretty comfortably of 5% to 5 a half% from investment grade types of Securities we can get that same yield on mortgage back Securities we can get towards around 6% on 9 agency cmbs which if if uh if approached properly uh we don't think has a lot of risk we'll talk we'll see that in a few minutes so there are some good yields out there Em High Yield is a 10% you should expect some defaults there but you have some room at 10% we see double uh doubleb Clos which are way up there at about 12% yield actually down a little bit on the year but there's some there's some high yielders out there but you have to be very careful about risk management and have active management and try to make sure you're going with somebody that's underwriting it correctly but it's it's not hard to get 6% out of a not very risky Bond portfolio which looks pretty good uh relative to the the landscape of inflation down even if it's even if it's three and a half you have a real yield there of two and a half percent it's over the FED funds rate uh and uh likely to be earned very comfortably here's spreads across fixed income sectors so again the the gold uh diamonds or rhombuses are uh year on 23 and then we got the blue bars are 2024 so we see spreads tightening everywhere during 2024 so mortgage index tightened a little bit credit tightened a little more IG tightened a little bit more than credit broadly ablea is about the same we see uh everything in the lower investment grade a little bit tighter on spread and then we get down to junk bonds they're all tighter they're at the alltime tights basically we'll see that triple c's came in a long way the leverage loans in and everyone um Triple C's uh in a little bit because people are worried about defaults and then we see uh in uh cmbs we see Triple B's in a lot huge outperformance there still lot still a lot of spread there uh double B's uh in Clo's in a lot Clos in a lot across the board and then Em High Yield did really well whereas em investment grade over on the right a little bit of spread movement so uh it was a good year for riskier bonds relative to low risk bonds the spreads came in okay so here's uh the speaks to the yield curve movement of 2024 what we have here is the uh Total return of each key rate on the treasury yield curve and then we have the month of December is in 10 so we see everybody was negative in December except for the two-year treasury so we see a huge yield steepening which we've been anticipating and positioned for for months now it's been working very well we see that in December the 30-year Bond had a horrible month of December down 6% in total return the 10e was down about half of that is what you'd expect given the duration difference and then if we take the year you see that the 2-year treasury was actually up three 3/4 and underperform t- bills see the 5-year treasury was slightly positive and then you start to go negative at the 10-year and it was another bad year for the 30-year treasury down 8% for 2024 not a good year think about that uh long Bond down 8% um S&P up 25% so I guess a 60/40 sort of worked uh gave you a return about 9% if you're using a long Bond here's uh 30-year treasury is going back to 1990 and this is what I mean by leaving the bus we've been in that bus from 1990 to 2020 and we were well contained in this series of the channels and now it's it's over you know we've broken out above it and here's what you has happened to you if you've owned the 30-year treasury uh if you owned it pre- pandemic you're still down over 50% on price on draw down so the 30-year treasury has not been a place uh to hide it certainly wasn't a place to hide during December um you know stocks did stocks did pretty well to end the year they're not doing well in the last couple of weeks the long Bond's not doing well either so I think that traditional thing somebody said to me if you think you know we in 40 years we haven't had a recession that didn't have long rates go down so why do you think long rates won't go down and I say because we're in a secularly different environment and that person responded oh so you're saying it's different this time i' I've been around long enough to know it's not that's the most dangerous expression I think it was John Templeton who said that in the investment business so I got news for you it is different this time this is not a secondly declining interest rate environment I think we can all agree that we will not repeat the 133% decline in long-term treasury yields experienced from 1980 the early mid 80s down to 2020 we're not going to go from a 1% 10e treasury rate to a negative - 12% treasury I think we can all agree on that so yes it it is the treasury market and the Market's price off of them it's going to be different this time we have left the bus we you're in a new environment and you've got to figure out how to navigate your new environment this is uh us Agate Bond index its longest draw Downs in the history of the index going back to 1976 this is the longest by a mile so yeah it's a little bit different this time now we the last time we had had draw Downs more than about a year and four months now it's 53 months and we hadn't had one that was 18% and now it's almost 18% so Uh something's different so let's go through some sectors here's the mortgage spread on agency mortgages and interestate volatility it's the same chart um if the if the FED uh stays where they are or has di Minimus as the market is forecasting a movement in fed funds rate in 2025 I think volatility will come down that should be good for agency morage Securities one thing you don't have in agency Mor Securities that are securitized is prepayment risk the coupon the average coupon uh on Mortgage Debt outstanding the interest rate that they took the mortgages out at is just below 4% it was lower than that but we've been populating with some sixes and sevens in the past couple of years but the current mortgage rate is about 7% so we're four we're 300 basis points out of the money so the one thing you don't have to worry about is uh refinancing in fact if you had refinancing it would probably be good because you're trading at a discount in the mortgage market so refinancing for the market broadly would be good but of course it would be the high coupons that refinance you don't want to be investing in in in uh in those uh after this rise in the 10year treasury so here's Assets in Money Market funds so this is one reason to be bullish on say five years and in in the bond market we see that the the money market assets went way up with all the money printing from the government in 2020 went to money markets because the the rate and and then we see that money markets have been the beneficiary of inflows still with the FED starting to cut rates we have a new leg in that and that's obviously because you now have higher rates on some bonds than you have on the FED funds rat which was at 5 and 38 or the six-month Bill we years ago people were talking about t- Bill and chill we recommended against that because the reinvestment risk we continue to advise against that because I think what's going to happen is Assets in my market funds are going to go to short and m-term bond funds and they should because you can get a 6% yield from those bond funds and the yield on the money on the FED funds rate is 4 and 38 may be predicted to go down to four by the end of the year so you'd have about a 200 basis point spread this is not a good argument for buying a a historically grossly overvalued Equity Market no one is going to go from a 5% yielding or 4% yielding money market fund into indivia you know that's not going to happen they're going to go they're going to go into other things that're riskier because they want higher yield but they're not going to go from the lowest risk thing into the highest risk thing I mean there's always somebody out there that'll do it but I don't think that's going to be a common activity maybe they'll go into some uh shorter term high quality uh bond funds because I'm here I'm just using investment grade but that's a good proxy for uh higher quality bond funds and look what's happened here the percentage of investment grade corporate bonds yielding less than 3-month T bill it went from 75% down to zero so there are no investment grade corporate bonds yielding less than the t- bill anymore so maybe some of those money market assets will move into lower risk intermediate term bond funds I would recommend you do that I've done it uh because not feeling that analyzing that that was the best for score place to be and as we've seen from some the charge it's prettyy much worked out here's um something that's interesting it's this spread between the lowest tier of high yield Triple C minus Double B so you get a pickup obviously when you go into uh Triple C you've lost some of that uh you you can see what's happened here is that spread has really really changed we have the blue line here which is that spread and then we have the moving a the Blue Line's we have the tan line which is the moving average so that blue line has come down a l long way it looks like you're not getting much compensation uh on a historical basis to own Triple C's that's why I think you stay in higher quality uh things Triple B Double B is not exactly high quality but certainly much higher than Triple C so here's defaults as they're developing for high yield and bank loans we'll see the yellow lines have been going up the bars yellow bars have been going up these are defaults that are not being characterized as defaults they're called uh pre-arranged exchanges or pre package chapter 11's distressed exchanges and we can distressed exchanges are the yellow bar prepackage chapter 11 is the is the light blue and we see together those make up about 75% of the defaults and in bank loans it's a little less but 70 so there's a lot of kind of stealthy defaults out there but defaults aren't that high we see that if you include those distressed exchanges high yield is only at 2 and 3/4% yes it's off the 2022 levels and moving a little bit higher but not alarming at this point loans up 4% that's kind of where they were uh during the the lockdowns so we we retrace back to that and then we see high and Loan recovery rates have gone up uh from 2022 but they remain pretty low I mean historically uh there was a an assumption that senior unsecured bonds would have like a 30% a 70 c recovery rate rather and then it was reduced down to 60 and it's really coming in at more like 40 whereas uh loans up at around 62% which I think the Assumption there is about 70% but it's been living below that for the last couple of years so here's spreads of non- agency cnbs by credit rating we see that we're all the way back to where we were pre pandemic pretty much on the aaa's the yellow lines same's true with the doublea's uh the single a is still a little bit elevated at 189 and the double the Triple B is still very elevated at 478 when it comes to our lower risk Bond strategies we invest in AAA and double A primarily and you can see the Market's not feeling distressed there with the FED not as aggressive as they were assumed to be six months ago you're more likely to keep your coupon on these floating red assets and so I think they're well supported here's the JP Morgan uh Global Diversified spread to worst On Em and the dollar Index and here's pretty interesting we see the spread to worst uh on the uh Global Diversified spread I is 640 and we see sorry the dollar Index is 110 and the spread to worse I mixed up the colors the red is the spread to worse that's come all the way down to 320 so in the past couple of years it's that spread has come in by you know 260 basis points or so so things were very cheap in 2020 2 and even in October 2023 really if you take a look at the context of the red line it's tighter than it was uh in 2020 2021 uh and not as tight as 2018 but uh with the dollar moving the way it is here it's kind of surprising that the spread hasn't been on a little more upward pressure there's questions of course I'm going to tr I tried to answer the ones that uh were common so will the dollar be devalued in when um it may be devalued it may be devalued in order to uh devalue the unfunded liabilities um those liabilities may also be re restructured so it's one or the other something has to happen the the dollars be devalued through inflation or the uh entitlements need to be restructured and the question asked when uh don't don't tell you know when when is difficult uh sometime in the future uh let's see any alternative to yield curve control if if so how does f portfolio navigate such an environment well if you believe in yield curve control what you're really saying is that they're going to issue bonds at artificially low rates which would be one way of handling the increase that's projected in the interest expense as a percentage of tax receipts is that you would just not allow the market to clear which is in a sense it's sort of quantitative easing which I mean the FED has sort of said they want to get the balance sheet down so that they're in a position to do more quantitative easing in the future they basically admitted that on adlib in one of the not the most recent couple press conferences but a fairly recent one they had yiel curve control between 1945 and the mid-50s and the rates were held below the inflation rate for about a decade and then began the massive Bond bear Market from the mid-50s into the 80s um that's the consequence of yield curve control when you try to prevent things using incrementalism you end up creating a high severity event that's gunlocks law of investment risk and that's now become gunlocks law of fire risk management if you try to incremental little things thinking that you're advancing some kind of an agenda in an incremental way and you incrementally let things SL flip on the fire safety side you end up with a catastrophic event and that's that's kind of what's happened here let's see we're kind of we're a little bit overtime here someone says are real yields of Two and a half% on long-term tips an attractive conservative investment um I'm very neutral on tips at these levels on the margin I think tips are attractive and I would certainly think that the CPI is not going to come down to 2% as a base case this year so it seems that tips are reasonably priced relative to a a five fivey year almost 10e but for the time being I think the CPI is not going to come down so the tips probably don't have a lot of risk on the downside um relationship between Rising crude oil prices and US tenure treasury I showed that chart is a lot more than year to date and yes um I'm in a fire zone there's last question on the going to wrap up on this yeah I'm in a fire zone I'm in evacuation Zone we've we've had fire on the property but not the house we've done everything we can we're hopeful in the days ahead that are the actions that we've taken will prove to be sufficient but there is very very little support in spite of all the taxes that get paid for to this to the county on property tax to the state on income tax there when the fires came last week there was literally no support whatsoever from anyone uh in the Palisades so the bills uh have three games to win before they Hoist the this the Lombardi trophy let's hope for that and with that we're going to wrap this up let's let's make the 2025 a better year than it started out to be but maybe we've taken our hits and it's all clear sailing going forward we want you to have a very successful 2025 we're very grateful for your suppor of double line good luck stay safe if you're in California California and goodbye for now


Comments 0