
저자: CharlieMunger—제목·설명기준발언자는CharlieMunger,진행자는Just-InvestToday채널운영자 · 외국인
요약 보기
결론: 찰리 멍거의 1973~74년 워싱턴포스트 투자 사례를 통해, 시장 폭락 시 단기 노이즈를 무시하고 내재가치에 집중해 저평가 기회를 잡아야 한다는 가치투자 교훈을 설명한 영상. [배경 및 투자 사례] 당시 S&P500은 약 -29%(영상 자막상 -24% 언급 포함) 하락했고, 워싱턴포스트는 워터게이트 사건으로 닉슨 행정부와 대립하며 패닉 매도를 맞았다. 멍거와 버핏은 내재가치 분석 결과 주가가 실제 가치의 약 1/6 수준이라고 판단해 약 1,000만 달러를 투자했고, 1~2년 내 약 10억 달러 규모로 불어났다고 설명. [핵심 논리] 가치투자자는 주가 변동 노이즈를 무시하고 오히려 그 노이즈에서 투자처를 찾는다. 시장이 효율적이라고 믿는 사람들이 주가를 '가치 그대로'로 여기는 점을 오히려 이용할 수 있다는 주장. [리스크 및 교훈] 멍거는 폭락을 예상하지 못했고 단기 손실도 겪었으나, 내재가치 대비 큰 할인 덕분에 감내 가능했다고 언급. 기회는 드물기 때문에 올 때 확실히 잡아야 하며, 빌리지 오일(Belridge Oil) 투자 기회를 자금 부족으로 놓친 것이 멍거의 최대 실수였다고 회고. [현재 시장 적용] 진행자는 알리바바가 내재가치 대비 크게 저평가되어 있다고 보고, 멍거가 알리바바에 큰 비중(20% 이상 추정 발언)을 투자한 것으로 해석하며 현 시장도 같은 기회라고 주장. [출연자 전망] 진행자는 현재 시장 기회를 강조하나 구체적 목표가나 기간은 제시하지 않음.
다듬은 글
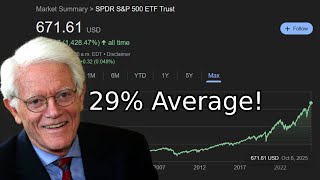
charlie munger's first podcast yes we're talking about it charlie munger actually went on a podcast called think with pinker and he talked about his washington post investments he added a lot of value he gave us a lot of insight on kind of what was going on in his thought process and what he was doing man and we have to understand what charlie munger does because it's important in these times right now people are down 30 40 50 on their investments they're looking all sad charlie munger came to the rescue you have to remember during that time when they invested in the washington post the market the s p had a negative 29 percent negative 24 during that time so it was a huge opportunity to get into the washington post and they had this scandal of the nixon administration for watergate so that provided a huge opportunity we're going to talk about charlie munger's strategies charlie monger's thinking and just what could you do and how can you actually become a better investor before we get into this video can you please like it subscribe to my channel i'm gonna be proud of you guys with so much new content man thank you like subscribe down below so the first question asked for charlie was you invested in the washington post at a time where everyone else thought it was on the way down is this an example of not getting distracted by the random fluctuations and he goes on to saying that investing is quite interesting if you look at the noise of the constant movement of stock prices value investors like charlie and warren they ignore all that random movement all that random noise and they focus on the intrinsic value of the company and when i thought about this i'm like this is amazing because they actually look for the noise they actually look for all the random movements to go to their hunting grounds to seek investments so that's their strategy they look to the noise to actually find investments because those are the ones providing the most random fluctuations and lower prices the newspaper was not yet a monopoly but they had a gold mine of network stations charlie and munger and warren buffett knew that they had so much intrinsic value in that but it didn't matter the time the stock prices crashed in 1973 and 74.
so all they did was look for the intrinsic value the short-term trading they happened to catch the war stock pionic since the stock collapse of the great depression in the collapse of the washington post because they got on the wrong side of the administration of the watergate scandal those two reasons caused the panic selling and then washington post got beat down for an unusual reason so that created the perfect hunting ground for charlie munger and warren buffett to look and that's when they found washington post as an amazing company to buy when they did the intrinsic value assessment of what was going on they found that that washington post was selling for one sixth of its actual price that what the market was giving it so guess what they did they bought it on top of the amazing bargain washington post had an amazing competitive durable advantage and that's what they were looking for so it was cheap and it had a durable competitive advantage a moat so it was a perfect stock to buy at that time but they end up putting 10 million into the stock and over the course of one to two years it already became a billion charlie munger goes on and says that he benefited from all the efficient market hypothesis saying that stocks are always valued at what they are valued at on the market so if you see a stock go from 100 down to 40 it's actually worth 40 no matter what's happening around it no matter the intrinsic value it's always worth 40 and they benefited from that people believing in the efficient market hypothesis and that's how they made so much money the next question was asked in the washington post investment you did lose some money and in the short term and were you anticipating that charlie says that no he was not anticipating that crash or anticipating losing money on that investment but it didn't matter to him all the noise didn't matter because he knew he was paying so much less than what the company wasn't worth 6x less than what it was worth and that's what he was paying for it so who wouldn't endure all that short-term knowledge and short-term problem washington post was worth it because it was the strongest newspaper in a big market and it was soon obviously going to destroy its competitors and be only newspaper in that market so an idiot could figure out that it was the enormous value selling at a huge discount from intrinsic value opportunities like that doesn't come too often but you don't need an opportunity like that very often once in a lifetime is enough so charlie munger goes on and says that he's a card player and not a good car player but he understands the opportunities that come along you have to go and grab it you can't blow it because you don't get a lot of opportunities in a card game so you have to take it and use it to your advantage and not a lot of people use this knowledge and put it to practical life so in the stock market you do not get a lot of opportunities and when you do you have to go out and grab it and when i think about this i think about alibaba honestly there's a lot of stocks in the market that have crashed 40 30 20 whatever but you have to grab the opportunities when you see them charlie monkey gives an example of bellridge oil this was his worst mistake he bought 300 shares right and the guy came back with 1500 more to give it to him but he didn't have the money to buy and he had to borrow the money but he had a bad experience borrowing the money so he didn't borrow the money one year later it went up 30 x and that's he said again and again that this was his biggest mistake he could have made so much more billions if he just had that mindset back then and took that opportunity when it was there because he knew it was selling under intrinsic value when i think about this i just think about alibaba in the market right now selling way below intrinsic value and that's how i see everything he's just connecting to right now we see that he bought a huge 20 chunk in alibaba i think he's taking that opportunity please like this video comment down below and subscribe to my channel please thank you



댓글 0