저자: 미상 · 외국인
요약 보기
나스닥 상장 AI 인프라 기업 NBIS(Nebius/Navitas 자막 오인식 추정)를 중립적으로 분석. 2분기 매출 5.82억달러(+454%), AI 클라우드 연환산 매출 30억달러, 400억달러 계약 잔고, 조정 EBITDA 마진 41%, 현금 80억달러가 강세 근거. 반면 마이클 베리의 GPU 감가상각 기간(5~7년) 문제 제기, 공매도 비중 약 24%, 58억 달러 전환사채 발행과 5.5% 희석, 전년 대비 주가 급등 후 과매수 지표가 약세 근거. 결론은 열린 질문으로 제시.
다듬은 글
Welcome to today's explainer. Today we're diving into the highly polarizing story behind Nebius Group, ticker NBIS. We'll walk through the fierce debate on Wall Street without taking a side, and look purely at the data and structural arguments driving both the excitement and the deep skepticism.
To understand why everyone is talking about Nebius right now, we have to start with the sheer scale of the situation. The stock has run up about 200% this year alone, pushing the company's market cap to around $60 billion. Even after today's 3.6% drop to $213.93, Nebius has captured the attention of institutional heavyweights looking for the next big thing and of large short sellers betting it will all come crashing down.
Here's the roadmap. First, we'll meet Nebius and its foundation. Then we'll weigh the bull case against the bear case, unpack the debt catalyst, compare growth with valuation, and wrap up with final takeaways.
Nebius isn't operating in a vacuum. It rests on three pillars. First, a powerful alliance with Nvidia for its AI cloud expansion, which gives it direct access to the highly coveted hardware that powers modern AI. Second, aggressive expansion, including a major UK deployment at Vantage Data Centers with 1.7 billion pounds of committed capacity. Third, a world-class engineering talent pool drawn from the former tech giant Yandex. Together these give Nebius a structural advantage that very few peers in AI infrastructure can match right now.
The financials show exactly why the bulls are roaring. In the second quarter, Nebius posted $582.3 million in revenue, a jaw-dropping 454% jump year over year. Almost all of it came from AI cloud revenue, which rose 514% to $575 million. That pushes the annualized run rate to a staggering $3.0 billion, up from $1.9 billion just one quarter earlier. Management is projecting up to $3.4 billion for the full year. Revenue is essentially quadrupling.
And it's not just current revenue; it's the pipeline. Nebius sits on a $40 billion contracted backlog, and the quality of those contracts is exceptional. They recently signed four large AI cloud deals, each averaging over $1 billion in total value. Customers are locking in long-term commitments for compute power.
What's especially interesting is how these contracts show up on the balance sheet. AI infrastructure is notoriously expensive to build, but Nebius's customers are pre-paying for capacity, covering 50% to 60% of Nebius's capital expenditures up front. That dynamic is driving strong margin expansion. AI cloud margins hit 49.7% in Q2, and the group's adjusted EBITDA margin expanded to 41%. Add $2.2 billion in Q2 operating cash flow, and Nebius ended June with a fortress-like $8 billion in cash and a 4.0x current ratio, meaning four times more liquid assets than short-term liabilities.
Unsurprisingly, Wall Street bulls are aggressive. Goldman Sachs recently upgraded the stock to a $328 target, citing strong demand and pricing tailwinds. Bank of America sits at $310, and Northland Securities has a $410 price target. The consensus average is $286.69, implying significant upside from current levels.
While analysts shout buy, a large portion of the market is betting on a collapse. Nearly 24% of the float, over 60 million shares, is sold short. To put that in perspective, it would take 2.4 days of average trading volume for the shorts to cover. The smart money is clearly circling.
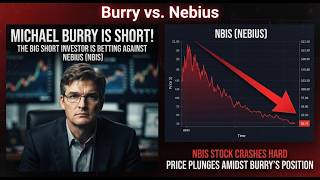
Among the short sellers is a familiar name, Michael Burry, the investor who famously predicted the 2008 housing crash. To be fair, he has also made a few calls that didn't pan out. He is publicly shorting Nebius, reportedly adding to his positions around the $212 and $259 levels. His thesis focuses on what we can call a depreciation time bomb.
The crucial point is how these companies account for their expensive hardware. Burry argues that AI infrastructure companies depreciate their GPUs over a five- to seven-year accounting life, while the rapid pace of the AI tech cycle means the hardware becomes functionally obsolete and needs replacing every two to three years. If he is right, the current profitability isn't a brilliant business model but an accounting illusion masking rapid equipment obsolescence.
The bears also point to structural concerns, starting with cash burn. In Q2 alone, capital expenditures hit $5.7 billion, a full billion above estimates. By 2026, Nebius anticipates spending $20 to $25 billion to procure GPUs and build data centers. And the market is getting crowded. Meta Platforms is reportedly considering leasing out its spare compute power, and SpaceX, Google, Anthropic, and even former Bitcoin miners are pivoting into AI infrastructure. If supply suddenly outstrips demand, GPU pricing power will fall, and Nebius's margins will fall with it.
Nebius has just doubled down on risk. It closed a $5.75 billion private offering of convertible senior notes. Management argues AI demand is insatiable and that it needs this growth financing immediately to fund data center construction and secure more GPUs.
The offering is split into two tranches. The 2030 notes raise $3.45 billion at a 0.50% coupon, with a conversion price of $344.81, a 54% premium. The 2034 notes raise $2.3 billion at a 4.50% coupon, with a conversion price of $405.82, an 81.3% premium. The premiums are high, but it is still a large amount of leverage to take on in a rapidly shifting technological landscape.
This is also why current shareholders care, and why the stock took a hit today. Alongside the new debt, the company swapped $800 million of existing notes for about 15.8 million new Class A shares. That introduces an immediate 5.5% dilution for existing shareholders. Participating holders can sell those new shares on the open market, creating immediate downward selling pressure.
It really comes down to a direct conflict. On the bull side, there's a $3 billion-plus annual run rate, and analysts like Piper Sandler project the company will scale to over $25 billion in revenue by 2028, with 10 strong buy ratings in support. On the bear side, there's the present: the stock trades at roughly 57 times sales and has a negative forward price-to-earnings ratio, meaning analysts expect it to lose money on a forward basis. Morgan Stanley's model projects a price target of just $144, implying major downside.
The technical charts reflect this conflict too. The daily stochastic hit 100, maximum overbought territory. The commodity channel index sits at 223, also deeply overbought. The stock trades well above its 52-week average. Yet despite these overbought warnings, trend momentum is strong enough that standard indicators still read a strong buy across daily, weekly, and monthly timeframes. The technicals are as conflicted as the fundamentals.
Whatever your personal lean, here is an objective roadmap. Keep your eyes on four core metrics. First, GPU pricing power: if capacity becomes less scarce as competitors enter, margins will compress. Second, capex efficiency: can they build out the $20 to $25 billion of capacity without overshooting actual market demand? Third, client concentration: will a giant like Meta become a competitor by leasing out its own compute? Fourth, the Burry trade: watch the accounting closely. If technology cycles force hardware write-downs faster than the five- to seven-year schedule, reported earnings could evaporate.
We'll leave you with a pivotal question. With a valuation of roughly 57 times sales, the execution risk here is historic. As the next few volatile quarters unfold, will Nebius prove itself as the world's next dominant hyperscaler, or are we watching the formation of the market's next great cautionary tale? Keep watching the data, and we'll see you in the next explainer.



Comments 0